MNI Fed Preview - Sept 2026: Analyst Outlook

Sep-14 19:43By: Tim Cooper
US
Hidden PDF
This update of our Sept 11 Fed preview includes analyst expectations - starting page 39
Sep 2026 FOMC Analyst Views: Shallow Hiking Cycle Expected
Consensus has capitulated in the direction of a 25bp September FOMC hike since last week’s inflation data, with only a handful of analysts seeing the Fed staying on hold this week and even then mostly with weak conviction.
- Among 35 analysts’ Fed previews (and media appearances Monday), just one is clearly calling for a hold (Jefferies, who still see the next move as a 25bp cut), while others have either acknowledged an extremely high chance of a hike while not publishing it as their base case in their preview (Danske, Morgan Stanley – not included in our table).
- Many analysts have shifted their Fed rate outlooks in a more hawkish direction. However, if we have not seen a forecast update since last week’s inflation data, we have not included the analyst's baseline outlook in our table.
- Statement: The overwhelming expectation is that there will be no major changes to the Statement. Attention will primarily be on dissents in favor of a hold: opinion is mixed, with some seeing no dissents, some 1, some 2 (Govs Bowman and Waller the primary candidates).
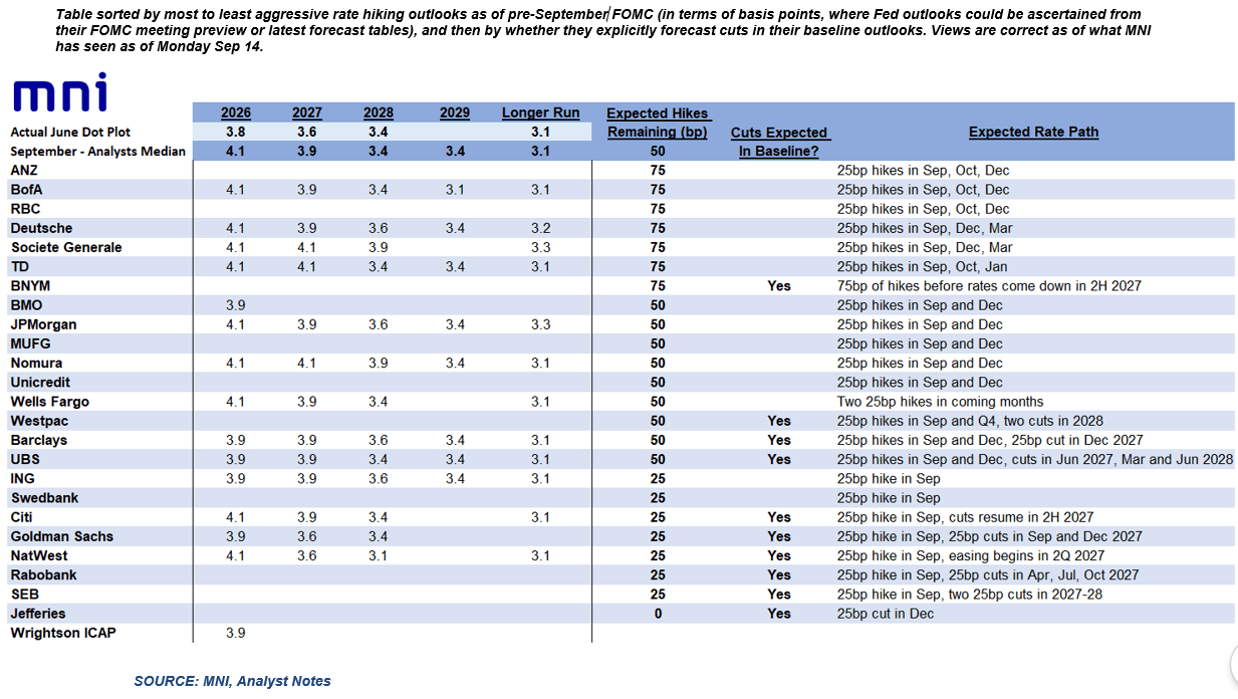
- SEP/Dot Plot: Given the widely expected hike, it’s no surprise that analysts see the September rate Dots moving up, with the 2026 median set to rise to 4.1% vs 3.8% previously, implying one more 25bp hike later this year after this week’s. However, opinion is split here (of the 15 analysts who published opinions, 9 see 4.1%, 6 see 3.9%).
- Additionally opinion is split on whether the Committee median will reflect an expectation for rate cuts in 2027; 7 analysts do, and 6 don’t. The 2027 median is expected overall to rise to 3.9% from 3.6% in June.
- As usual, analysts expect cuts to be reflected further out, with the new 2029 median Dot reflecting a 3.4% rate. A few analysts see the longer-run median shifting up from 3.075% previously; the most notable are SocGen and JPMorgan who see the median rising to 3.25% (Deutsche sees 3.2%, likely reflecting a split between 3.125% and 3.25%).
- Macro Projections: Analysts are largely agreed that the unemployment and GDP forecasts won’t be changed much vs June’s round, with the unemployment rate expectation due to be slightly lowered given recent readings.
- More controversial is the outlook for the PCE inflation medians, with some analysts expecting participants to incorporate the methodological change for PCE due later this month that should lower the 2026 core projection (from 3.3% in June), though others see the forecast rising on account of recent data. On this front, UBS observes “the median dot has never revised up for the same year that median core PCE inflation revised down 0.2 pp or more.”
- Future action: The median expectation is for 50bp of hikes, for the most part by early 2027, with the most hawkish analysts seeing 75bp. About half of analysts see cuts coming soon thereafter. As noted, one analyst still sees the next move being a cut (Jefferies), while at least 7 analysts (including Citi, Goldman, and NatWest) see September’s hike as a “one and done”.