MNI Fed Preview - March 2026: Navigating A Narrow Strait

Mar-13 21:08By: Tim Cooper
US
Hidden PDF
EXECUTIVE SUMMARY
- The FOMC will hold the Federal Funds rate at 3.50-3.75% for a second consecutive meeting in March, in what increasingly looks like a prolonged pause before the next move.
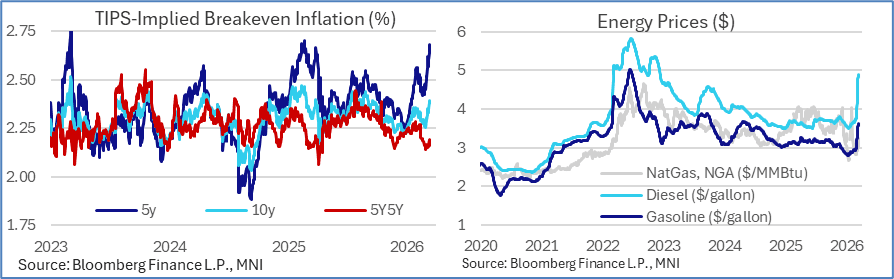
- The outlook for policy changes has been complicated by events in the Middle East. With energy prices soaring, markets have swung from anticipating two 25bp rate cuts this year to now not even pricing one fully.
- The updated Dot Plot is likely to show the same median expectation for the rate path as December’s, including one 25bp cut by end-2026, which combined with a largely unchanged statement will effectively maintain the easing bias.
- Incoming data for the year so far won't allay hawks’ skepticism that inflation is headed sustainably to 2%, and while job gains remain soft at best, the labor market hasn't deteriorated to the point once feared.
- The threat posed to both dual mandate variables from the conflict in the Middle East gives policymakers even more reason to wait and see how things develop.
- We suspect that most on the FOMC, including the core leadership, will be more concerned with the potential demand destruction from the ongoing energy supply-side shock, than with the inflationary implications.
- But this is no time for pre-emptive action given inflation remaining above-target and expectations beginning to pick up, and it will take some months before a case can be made to resume easing.
MNI’s separate preview of sell-side analyst summaries to follow on Monday March 16