MNI ECB Review: September Hike Unsurprisingly Tee’d Up

Jul-23 16:54By: Chris Harrison and 1 more...
Eurozone
Hidden PDF
Executive Summary
- The ECB left its three key rates on hold as widely expected, including the deposit rate at 2.25%.
- The initial decision statement was particularly short, taking a page out of Fed Chair Warsh’s book, whilst maintaining optionality.
- President Lagarde’s press conference played up to market pricing, i.e. a strong likelihood of a hike at the following meeting in September after almost zero expectation of action today, whilst remaining open-ended ahead of a busy seven-week period until the next decision.
- We view Lagarde thinking the ECB’s reaction function is “well understood” by markets as implicit endorsement of the hiking profile priced in.
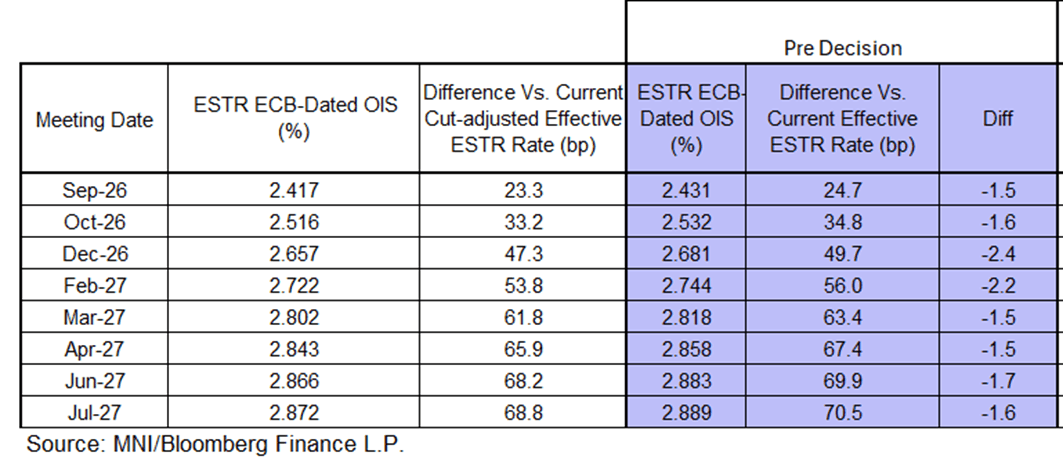
- There was a mildly dovish move in ECB rates over the suite of communications but it’s small compared to the hawkish build-up ahead of the meeting as energy prices continued to surge.
- There is still close to 50bp of hikes priced by year-end, leaning towards a quarterly hiking cadence with projection meetings.
- Bloomberg sources echo near-term pricing in looking for a September hike unless the inflation outlook improves markedly, which also chimes with pre-meeting MNI source reporting.