INDONESIA: MNI BI Preview Rpt– Sept 2026: Hold, Retain Tightening Bias
* Download full preview here: https://mni.marketnews.com/4xJmNTA. Bank Indonesia Preview with comp...
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
FOREX: JPY Leveraged Shorts Added Too, But Mostly USD Selling Elsewhere - CFTC
Last week's CFTC FX positioning update (for the week ending Aug 18) was predominantly skewed against the USD across both the leveraged space and for asset managers (see the table below). The USD trend only worsened post last week's CFTC update, with the BBDXY index testing sub 1190. In terms of positioning shifts against the USD, the exception was JPY, where leveraged contracts expanded net shorts. This is the first increase in net shorts since the end of July, while outright shorts remain in from recent cycle wides (-137.8k recorded at the end of June). Since the strong intervention episode form late July, USD/JPY dips have been supported, although the pair ran out of steam closer to 160.00, aided by broader USD weakness late last week, as US Tsy's buyback weighed more broadly on dollar sentiment. Yen has been a laggard relative to G10 FX gains versus the USD in recent weeks, particularly relative to higher beta plays. This may keep yen leveraged shorts comfortable, even without USD/JPY breaking back above 160.00.
- Outside of MXN net selling, other leveraged position shifts were all against the USD. The aggregate moves weren't large, but in markets like NZD, net shorts continue to be challenged (NZD/USD is eyeing an upside test of 0.6000).
- In the asset manager space, it was a similar theme, where the USD was mostly sold (except for AUD). Strong EUR, CAD and MXN buying by this segment were the standouts.
Table 1: CFTC Weekly Change & Outright FX Positioning By Major Currency (Aug 18 2026)
| Leveraged Contracts | Asset manager Contracts | |||
| Weekly Change | Outright Position | Weekly Change | Outright Position | |
| JPY | -14115 | -73641 | 614 | -23601 |
| EUR | 1636 | -76035 | 12140 | 266460 |
| GBP | 3348 | 46070 | 2185 | -117885 |
| AUD | 4022 | 49749 | -5553 | -48650 |
| NZD | 6617 | -27414 | 3788 | -25459 |
| CAD | 2651 | -89836 | 15070 | -89180 |
| CHF | 2549 | -11512 | 1252 | -37070 |
| MXN | -10940 | 65468 | 27966 | 62152 |
Source: Bloomberg Finance L.P./MNI
NEW ZEALAND: Cost-Of-Living Pressures Drive Spending Pullback
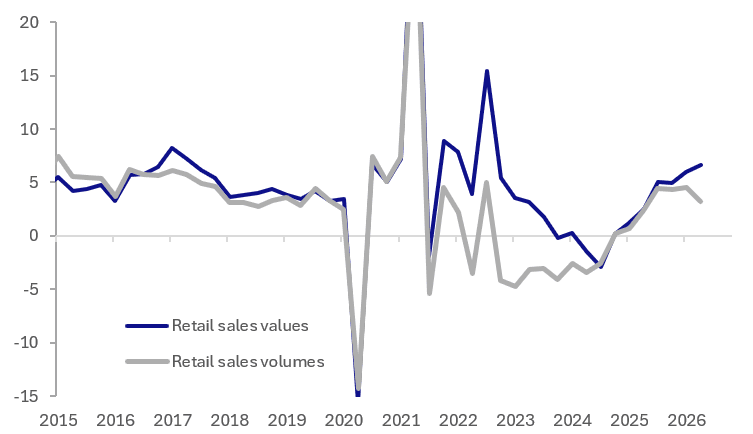
Q2 real retail sales fell 0.5% q/q and slowed to +3.2% y/y from 4.5%. It was the weakest quarterly read for two years as higher fuel prices drove a drop in volumes purchased and weak discretionary spending. While the RBNZ is likely to follow up July’s hike with another on 2 September, there is a growing collection of data suggesting an easing of pressure to hike at every meeting, thus there may be a pause in October.
- Nominal sales rose 0.9% q/q in Q2 to be up 6.6% y/y after Q1’s 5.9%. Prices are adding considerably to retail values, especially fuel prices in Q2. The sharp rise in fuel following the onset of the Iran War drove a substantial drop in fuel purchases (-13% q/q) contributing to the overall decline in sales volumes in the quarter.
NZ retail sales volumes vs values y/y%
Source: MNI - Market News/LSEG
- Eight of the 15 sectors recorded declines in sales volumes but some were impacted by the conflict and uncertainty in the Middle East, including motor vehicles and accommodation. However, department stores, food services and recreational goods fell while liquor, clothing and supermarkets were flat. Apart from the latter, these are more discretionary sectors and reflect households cutting back on rising cost-of-living pressures and lower confidence. However, electrical goods saw the sharpest rise (+9.2% q/q).
JGBS: Futures Weaker Overnight On Friday With US Tsys, Light Local Calendar
In post-Tokyo trade, JGB futures closed weaker, -10 compared to settlement levels, after US tsys finished Friday's session 2-5bps cheaper, with a flatter curve.
- Early trade on Friday saw the drift higher in US yields halted around 730am ET on a report that Iranian President Pezeshkian was in favour of ending the war with the US, but the impulse faded after further comments were decidedly less conciliatory.
- Cash US tsys came under significant pressure at around 9am ET in a bear flattening move, with 2Y yields rising 6bp to a high of 4.2501% and a Fed hike going from partially (22bp) to fully (26bp) priced by year-end. There was no clear catalyst for the move but it confirmed that the cash curve bear flattened for the week, a directional shift that of course was helped by Treasury's surprise announcement Wednesday that it was upping long-end buybacks.
- "Sanae Takaichi's cabinet support fell 3.5 points to 50.2%, a record low, according to a Kyodo poll." - BBG
- Today, the local calendar will be empty apart from 10-year Climate Transition supply.
Bloomberg Finance LP


