MNI ASIA MARKETS ANALYSIS: US/Iran Negotiations Still in Limbo
HIGHLIGHTS
- Cleveland Fed Hammack says that "for today, it’s reasonable to keep rates steady given the uncertainties around the economic outlook. But if recent trends continue, it may soon be appropriate to act.
- Uncertainty over US/Iran war negotiations tempered risk sentiment Tuesday - at least for the SPX emini and Nasdaq indexes - as they drifted off Monday's record highs (7631.25 and 27190.21 respectively), while the DJIA managed to a new record high of 51340.33.
- Australian Q1 GDP highlights Wednesday’s data calendar, while attention will be on a crucial speech by BOJ Governor Ueda to business leaders, expected to provide greater clarity on policymakers’ intentions. Later on Wednesday, US ADP, ISM Services PMI and Beige Book are scheduled.
- US May Employment report to be released Friday, recent improvement in various labor market metrics has seen the FOMC increasingly focus on upside inflation risks, which are likely to remain in the driving seat when it comes to rate hike expectations.
US TSYS
MNI US TSYS: Job Openings Jump, Crude Rises Amid Ongoing Middle East Uncertainty
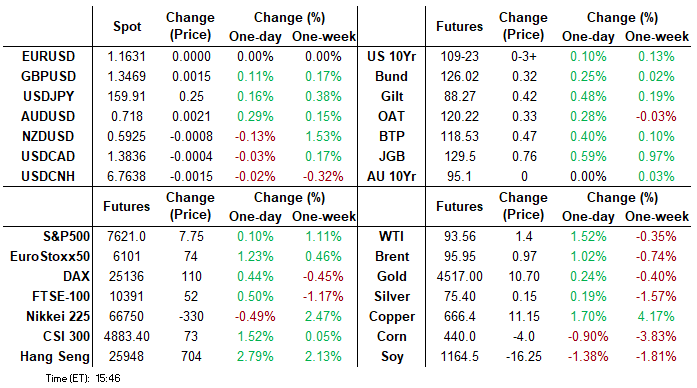
- Treasuries are modestly firmer after the bell, bottom half of the range after JOLTS job openings climbed unexpectedly, a precursor to tomorrow's monthly ADP and Friday's NFP. Crude prices bounced (WTI +1.41 at 93.57) amid ongoing Middle East uncertainty.
- TYU6 trades +4 at 109-23.5 after the bell, 10Y yield -.0020 at 4.4512%; holding on to their recent gains, the medium-term trend set-up remains bearish and recent gains are considered corrective - for now.
- JOLTS job openings were far higher than expected in April at 7.62mn (sa, cons 6.87mn) after a barely revised 6.89mn in March (initially 6.87mln). It’s notable however that this increase was concentrated by the professional & business services industry reporting 1.715mln openings vs 1.047mln in March, a 668k monthly increase compared to the 684k for private industries and 731k overall.
- Released on Friday, Jun 5, nonfarm payrolls are seen increasing by 85k in May (primary dealer median 95k) after a surprisingly strong 115k increase in April followed some particularly volatile months in Q1.
- Cleveland Fed Pres Hammack (hawk, 2026 voter), who dissented at the April meeting in favor of removing the easing bias from the statement, eyes potential Fed hikes "soon" if "recent trends continue" per a speech Tuesday.
- USDJPY has been making slow but steady progress higher in recent sessions, with today’s price action indicative of current sentiment; that long USDJPY remains a popular fundamental trade with very obvious attached caution related to the high likelihood of renewed verbal warnings and actual intervention.
- A geopolitical headline from the Guardian summed up uncertainty nicely: that Sec of State Marco "Rubio says Iran ready to discuss nuclear deal as Tehran declares peace talks over." Meanwhile, continued fighting in southern Lebanon today, throws doubt on US President Donald Trump's claim that he had negotiated a ceasefire extension with both Israel and Hezbollah.
REFERENCE RATES
US TSYS: Repo Reference Rates
- Secured Overnight Financing Rate (SOFR): 3.65% (+0.02), volume: $3.224T
- Broad General Collateral Rate (BGCR): 3.63% (+0.02), volume: $1.301T
- Tri-Party General Collateral Rate (TCR): 3.63% (+0.02), volume: $1.278T
- (rate, volume levels reflect prior session)
STIR: FRBNY EFFR for prior session:
- Daily Effective Fed Funds Rate: 3.62% (+0.00), volume: $123B
- Daily Overnight Bank Funding Rate: 3.62% (+0.00), volume: $241B
FED Reverse Repo Operation
RRP usage at $2.502B with 32 counterparties this afternoon vs. $1.302B Monday. Compares to last year's highest excess liquidity measure: $460.731B on June 30.
US SOFR/TREASURY OPTION SUMMARY
SOFR & Treasury options trade outlined below: modest early summer volumes in play - tending towards wing buyers and 10Y vol sales via strangles. Underlying futures still bid - but well off morning highs. Projected rate pricing consolidates slightly from late Monday's hawkish view (*): Jun'26 at +.5bp (+1.4bp), Jul'26 at +2.1bp (+3bp), Sep'26 at +7.1bp (+8bp), Oct'26 at +10.6bp (+11.2bp), Dec'26 +17.6bp (+18.4bp).
SOFR Options:
-5,000 SFRU6 96.37/96.50/96.75 2x3x1 broken put flys, 1.0/wings over
+30,000 SFRU6 96.87/98.62 call spds, 1.25 ref 96.255
-3,500 SFRZ6 95.86/96.12/96.37 iron flys, 19.25
+3,000 SFRH7 96.25 calls, 22.0 vs. 96.07/0.40%
+2,000 SFRV6 96.00 puts, 12.75 vs. 96.15/0.38%
-2,000 SFRM6 96.37 calls, .25 ref 96.33
+2,000 3QM6 96.12/96.25 put strip, 6.0 vs. 96.185/0.35%
+5,000 SFRZ6 96.37/96.62/96.75 call flys, 0.5 ref 96.155
+32,000 SFRN6 96.87/97.12 call spds, cab
+2,000 SFRZ6 95.37 puts, 5.5
+3,000 3QM6 96.12/96.25 put spds, 6.0 vs. 95.185
1,250 0QZ6 95.50 puts
3,000 SFRZ6/0QZ6 95.75/96.00 put spd spds
2,000 SFRM6 96.43/96.56/96.62/96.68 put condors ref 96.34
1,300 0QM6 95.93 puts ref 96.07
Treasury Options:
-7,500 TYQ6 108.5/111 strangles, 42 ref 109-23.5
7,500 TYN6 107.5 puts, 3 ref 109-24
+2,000 TYN6 110 puts, 33 ref 110-01/0.53%
+3,000 wk2 TY 108.5/109/109.5 put trees, 5 vs 109-30.5/0.05% (exp 6/12)
+5,000 wk1 TY 110.5 calls, 3
+2,500 TYU6 114.5 calls, 6 ref 109-28.5
over 5,000 TYN6 111.75 calls, 3-4 ref 109-30 to -25
8,000 FVN6 109.5 calls, 1 last
+3,000 wk2/wk1 TY 109.5 put spds, 8 net
MNI BONDS: EGBs-GILTS CASH CLOSE: Short End Continues To Underperform
European yields fell Tuesday, with the short-end continuing its underperformance this week.
- The overnight session saw modest gains in Bund and Gilt futures that brought them to what would be session highs, after US President Trump's comments late Monday pointing to a detente between Israel and Hezbollah in Lebanon, and Iranian media reporting Tehran was mulling a final text on a memorandum of understanding on a deal with the US.
- But the nascent rally would begin reversing around midday London time, as crude prices begin to recover, exacerbated by a Fars report that there were currently no talks between the US & Iran. Better-than-expected US jobs opening data also helped diminish the dovish tone.
- In data, flash May Eurozone HICP came in almost exactly in line with consensus but core was stronger than expected; UK lending data for April were mixed.
- BOE's Greene continues to sound as if she will potentially vote for a June hike, while Bailey's comments were in line with previous.
- On the day, the UK and German curves bull flattened, partially reversing the prior session's bear flattening but with the short-end continuing to underperform. Periphery/semi-core EGB spreads to Bunds tightened modestly, led by BTPs.
- Wednesday's calendar includes final services/composite PMIs and Eurozone PPI, along with multiple ECB speakers.
Closing Yields / 10-Yr EGB Spreads To Germany
- Germany: The 2-Yr yield is down 1.1bps at 2.62%, 5-Yr is down 2.3bps at 2.693%, 10-Yr is down 2.8bps at 2.975%, and 30-Yr is down 2.1bps at 3.521%.
- UK: The 2-Yr yield is down 1.6bps at 4.31%, 5-Yr is down 3bps at 4.424%, 10-Yr is down 3.9bps at 4.859%, and 30-Yr is down 4.5bps at 5.549%.
- Italian BTP spread down 2bps at 71.5bps / French OAT down 1.3bps at 61.7bps
MNI OPTIONS: Dovish Euribor Structures Buying Remains Prevalent
Tuesday's Europe rates/bond options flow included:
- RXN6 125/124 ps sold at 13.5 in 4.7k
- ERN6 97.31/97.37/97.50/97.56c condor, bought for 3 in 5k
- ERQ6 97.43/97.50/97.56/97.62c condor, bought for 1.5 in 10k
- ERQ6 97.56/97.62/97.68c ladder, bought for 0.75 in 8k
- ERU6 97.8125/97.875 call spread, paper pays 0.25 in 5k
- ERZ6 97.56/97.75/97.93c fly, bought for 3.5 in 4.25k
MNI FOREX: USD Tilts Higher Amid Oil Bounce, AUDNZD Recovery Extends
- Oil prices have rallied around $3 from the lows across the US session, and while this has biased the US dollar higher, net adjustments across the G10 FX space remain very contained. The Australian dollar is a moderate outperformer on the session, with AUDUSD currently up 0.28% as we approach the APAC crossover. RBA’s Harper may have assisted this sentiment, noting the concerning development that Australia’s longer-term inflation expectations have edged higher, while the announcement of a 4.75% minimum wage increase was above expectations.
- With AUDNZD (+0.4%) remaining in focus after last week’s sharp pullback, today’s dynamics have allowed the cross to edge higher and retake the 1.21 handle. Spot is now testing back at the 50-day EMA (1.2108), while the 50% retracement of the recent pullback is located at 1.2136.
- Short-term gains in EURUSD appear corrective at this juncture, helped by key resistance at 1.1672, the 50-day EMA, broadly being respected. Attention remains on 1.1603, a 1.00 projection of the Apr 17 - 30 - May 6 price swing, and 1.1557, the bear channel base. A break of both levels would strengthen a bearish threat.
- On the topside, a clear break of the 50-day would signal scope for a stronger recovery towards a bear channel resistance at 1.1721. The channel is drawn from 1.1849, the Apr 17 high.
- Australian Q1 GDP highlights Wednesday’s data calendar, while attention will be on a crucial speech by BOJ Governor Ueda to business leaders, expected to provide greater clarity on policymakers’ intentions. Later on Wednesday, US ADP, ISM Services PMI and Beige Book are scheduled.
MNI JPY: USDJPY Approaching 160.00 Ahead of Ueda, Watch Out for Mimura Comments
- USDJPY has been making slow but steady progress higher in recent sessions, with today’s price action indicative of current sentiment; that long USDJPY remains a popular fundamental trade with very obvious attached caution related to the high likelihood of renewed verbal warnings and actual intervention.
- This is highlighted by the fact USDJPY is trading just 10 pips of shy of what many in the market believe to be the MoF’s line in the sand at 160. While a test won’t necessarily prompt an immediate response, the close proximity to cycle highs at 160.72 will be alarming for officials. One could argue that looking at Citi’s broad real effective exchange rate, new cycle lows may already be ringing those alarm bells.
- BOJ Governor Ueda’s speech on Wednesday has received attention, given there could be clear hints relating to the BOJ’s bias into the June meeting. However, the market may be more sensitive to any comments from the nation’s top currency official, Atsushi Mimura. As a reminder, it was the “final” warning from Mimura that preceded record levels of actual intervention, just hours after the remarks.
MNI OPTIONS: Expiries for Jun03 NY cut 1000ET (Source DTCC)
- EUR/USD: $1.1625-35(E2.4bln) $1.1700-01(E2.0bln), $1.1740-50(E1.6bln), $1.1850(E1.5bln)
- USD/JPY: Y159.75($1.2bln)
- AUD/USD: $0.7200(A$771mln)
- USD/CAD: C$1.3830($673mln)
MNI US STOCKS: Late Equities Roundup: At/Near Recent Highs
- Uncertainty over US/Iran war negotiations tempered risk sentiment Tuesday - at least for the SPX emini and Nasdaq indexes - as they drifted off Monday's record highs (7631.25 and 27190.21 respectively), while the DJIA managed to a new record high of 51340.33. Currently, the DJIA trades +0.48%, SPX eminis +0.05%, the Nasdaq -0.1%.
- A geopolitical headline from the Guardian summed up uncertainty nicely: that Sec of State Marco "Rubio says Iran ready to discuss nuclear deal as Tehran declares peace talks over."
- Meanwhile, continued fighting in southern Lebanon today, throws doubt on US President Donald Trump's claim that he had negotiated a ceasefire extension with both Israel and Hezbollah.
- IT and Utility sector shares outperformed in the second half, semiconductor shares buoyed the former: Coherent Corp and Hewlett Packard Enterprise both rising approximately 16.75%, Lumentum Holdings +14.25% while Corning Inc gained 12.9%.
- Electricity and independent power shares supported the Utility sector, the following trade +2.7 to 3.4% higher: NRG Energy Inc, Constellation Energy Corp, PG&E Corp, Entergy, Dominion Energy and Edison International.
- Communication Services sector underperformed lat eTuesday, followed by Health Care sector shares, the following -3.75-4.5%: Veeva Systems Inc, Charles River Laboratories Int, IQVIA Holdings and Insulet Corp.
MNI EQUITY TECHS: E-MINI S&P: (M6) Bulls Still In The Driver’s Seat
- RES 4: 7700.00 Round number resistance
- RES 3: 7652.24 3.618 proj of the Apr 23 - 28 - 29 price swing
- RES 2: 7635.25 3.500 proj of the Apr 23 - 28 - 29 price swing
- RES 1: 7632.25 High Jun 1
- PRICE: 7619.50 @ 1455 ET Jun 2
- SUP 1: 7439.53 20-day EMA
- SUP 2: 7293.50 Low May 6
- SUP 3: 7234.52 50-day EMA
- SUP 4: 7131.25 Low Apr 29
The primary trend in S&P E-Minis remains bullish and a fresh cycle high yesterday reinforces bullish conditions. The break higher maintains the bullish price sequence of higher highs and higher lows. Note that moving average studies are in a bull-mode position, highlighting a dominant uptrend. Sights are on 7635.25, a Fibonacci projection. Initial firm support to watch is 7439.53, the 20-day EMA.
MNI COMMODITIES: Crude Rises Amid US-Iran Deal Uncertainty, Gold Steady
- Crude prices have risen today amid uncertainty around US-Iran deal prospects, as Iran continues to assert that it is not communicating with the US at present. Crude remains below yesterday’s high after Israel and Hezbollah agreed to a deal that could limit each side’s attacks.
- WTI Jul 26 is up by 1.7% at $93.7/bbl.
- Israel’s Defence Minister said that the US has backed Israeli strikes on Beirut suburbs if attacks continue on north Israel. Meanwhile, Israeli forces continued attacks across southern Lebanon on Tuesday, according to Middle East Eye, citing reports from the ground.
- US Secretary of State Rubio said that there is ‘a prospect’ that Iran will discuss further aspects of its nuclear programme in discussions.
- A primary bull cycle in WTI futures remains intact and recent weakness appears corrective. Key resistance has been defined at $105.21, the May 18 high, a clear break of which would resume the primary uptrend.
- On the downside, key support is at $90.23, the 50-day EMA. A clear breach is required to highlight a top and the start of a stronger correction.
- Elsewhere, gold is little changed today, amid a stable US dollar, with spot holding around $4,489/oz.
- From a technical perspective, the trend set-up in gold remains bearish, with scope seen for an extension towards $4,306.4, the Mar 24 low.
- For bulls, initial key resistance has been defined at $4,773.5, the May 12 high. Clearance of this hurdle would be a bullish development.
WEDNESDAY DATA CALENDAR
| Date | GMT/Local | Impact | Country | Event |
| 03/06/2026 | 0715/0915 | ** |  ES | S&P Global Services & Composite PMI (f) |
| 03/06/2026 | 0745/0945 | ** |  IT | S&P Global Composite & Services PMI (f) |
| 03/06/2026 | 0750/0950 | ** |  FR | S&P Global Composite & Services PMI (f) |
| 03/06/2026 | 0755/0955 | ** |  DE | S&P Global Composite & Services PMI (f) |
| 03/06/2026 | 0800/1000 | ** |  EU | S&P Global Composite & Services PMI (f) |
| 03/06/2026 | 0830/0930 | ** |  GB | S&P Global Composite & Services PMI (Final) |
| 03/06/2026 | 0900/1100 | ** | EU | EZ PPI |
| 03/06/2026 | 0900/1000 | * | GB | Index Linked Gilt Outright Auction Result |
| 03/06/2026 | 0950/1150 | EU | ECB Elderson Keynote at Goldman Sachs European Financials Conference | |
| 03/06/2026 | 1100/0700 | ** |  US | MBA Weekly Applications Index |
| 03/06/2026 | 1200/0800 | * | US | NY Fed SOFR |
| 03/06/2026 | 1300/0900 | US | Fed Governor Michael Barr | |
| 03/06/2026 | 1300/0900 | * | US | NY Fed EFFR |
| 03/06/2026 | 1330/1530 | EU | ECB Cipollone Statement at Digital Euro Hearing | |
| 03/06/2026 | 1345/0945 | *** | US | S&P Global Composite & Services Index (final) |
| 03/06/2026 | 1400/1000 | *** | US | ISM Non-Manufacturing Index |
| 03/06/2026 | 1400/1000 | ** | US | Factory New Orders |
| 03/06/2026 | 1400/1000 | ** | US | Factory New Orders |
| 03/06/2026 | 1430/1030 | ** | US | US DOE Petroleum Supply |
| 03/06/2026 | 1430/1030 | ** | US | DOE Weekly Crude Oil Stocks |
| 03/06/2026 | 2000/1600 | US | Dallas Fed's Lorie Logan | |
| 04/06/2026 | 0130/1130 | ** |  AU | Trade Balance |


