MNI ASIA MARKETS ANALYSIS: New Nasdaq Highs as Crude Retreats
HEADLINES
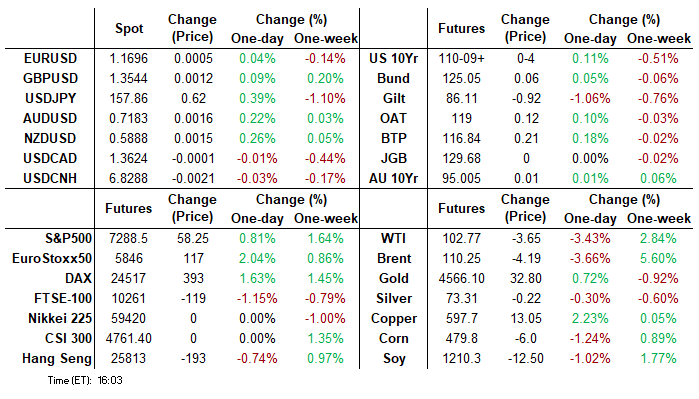
- Treasuries recovered a small fraction of the week opener's sell-off, sentiment slightly improved as crude prices retreated even as geopolitical tensions in the Middle East remain.
- Oil prices retreated as the US downplayed Iranian attacks on Monday ading the ceasefire still in effect. This follows the surge in crude yesterday after strikes on the UAE and reports of exchanges of fire between the US and Iran over vessel transits via the Strait of Hormuz.
- GBP's resilience continues to standout. Further stress evident in UK bond markets helped push benchmark 30y Gilt yields to the highest levels since the late 1990s, further widening the spread against German bonds as an indicator of relative fiscal weakness.
- Indiana state primary elections today will provide data on the influence President Donald Trump wields over the GOP ahead of November's midterm elections. Polls close at 18:00 ET 23:00 BST, with results expected shortly after.
- LOOK AHEAD: Wednesday Data Calendar: ADP, Treasury QRA, Fed Speakers
US TSYS
MNI US TSYS: ISMs, Jobs & Softer Crude Prices Buoy Tsys Ahead Wednesday's ADP
- Treasuries gained after ISM Services prices paid came out lower than expected, as did New Orders. Additional factors supporting Tsys & stocks: crude prices continue to decline: June WTI contract dipped to appr low of $101.0/bbl to $102.70/bbl late.
- The ISM services index was very close to expectations in April at 53.6 as it dipped slightly from 54.0 in March to extend a drop from February’s 56.1 (highest since Jul 2022). Details were on balance dovish relative to expectations, with the prices paid index unchanged and new orders slipping more than expected vs employment broadly in line, with the usual caveat of more limited surveys for the components.
- Meanwhile, March JOLTS job openings vs. Feb declines less than expected while Quits and Layoffs levels surge higher: Job openings were slightly higher than expected in March at 6866k (sa, cons 6850k) for a small decline after an upward revised 6922k (initial 6882k) in February. The quits rate was a little more encouraging on the month at 2.00% after 1.92% but again continues to broadly plateau. It has averaged a relatively low 2.0% since late 2024 vs the 2.3% in 2019 or 2.2% through 2017-18
- Off the morning high of 110-15, TYM6 trades 110-09.5 (+4). A bearish theme in Treasuries remains intact - MA studies are in a bear-mode position, highlighting a dominant downtrend. Key S/T resistance has been defined at 111-27+, the Apr 17 high. A continuation lower would expose the bear trigger at 109-24, the Mar 27 low. Clearance of this support would confirm a resumption of the downtrend.
- Indiana state primary elections today will provide data on the influence President Donald Trump wields over the GOP ahead of November's midterm elections. Polls close at 18:00 ET 23:00 BST, with results expected shortly after.
REFERENCE RATES
US TSYS: Repo Reference Rates
- Secured Overnight Financing Rate (SOFR): 3.63% (-0.01), volume: $3.113T
- Broad General Collateral Rate (BGCR): 3.61% (-0.02), volume: $1.279T
- Tri-Party General Collateral Rate (TCR): 3.61% (-0.02), volume: $1.253T
- (rate, volume levels reflect prior session)
STIR: FRBNY EFFR for prior session:
- Daily Effective Fed Funds Rate: 3.64% (+0.00), volume: $111B
- Daily Overnight Bank Funding Rate: 3.63% (+0.00), volume: $231B
FED Reverse Repo Operation
RRP usage at $1.122B with 6 counterparties this afternoon vs. $.618B Monday (highest since April 7). Compares to last year's highest excess liquidity measure: $460.731B on June 30.
US SOFR/TREASURY OPTION SUMMARY
SOFR & Treasury options trade outlined below: Puts remain in focus albeit two-way as volumes gradually improved. Tsy options saw a pick-up in 10Y calls. Underlying futures a little firmer after Monday's sell-off. Projected rate pricing near flat through the fall, latest levels vs. late Monday lvls (*): Jun'26 at -1.5bp (-.7bp), Jul'26 at -3.1bp (-1.6bp), Sep'26 at -2.0bp (-0.5bp), Oct'26 at +1.9bp (+3.4bp), Dec'26 +6.7bp (+8.1bp).
SOFR Options:
Block/screen, 26,400 SFRZ6 96.06 puts, 19.75 ref 96.23 to -.235
-5,000 SFRH6 96.12/96.25 put spds, 5.0
-6,000 SFRH8 95.50 puts, 28.5 vs. 96.355/0.25%
+8,000 SFRZ6 96.12/96.37 put spds, 10.5 ref 96.25/0.15%
2,000 SFRN6 96.06/96.25/96.37 put fly
+20,000 SFRZ6 96.12/96.37 put spds, 10.5 vs. 96.245/0.15% (+25k yesterday/unwind)
+30,000 SFRM6 96.25/96.31 put spds, .25
4,000 0QU6 97.25 calls ref 96.245
-2,500 SFRZ6 96.43/96.62 call spds, 4.75
-2,500 SFRZ6 95.50/95.75 put spds, 3.75
-1,750 SFRZ6 96.43/96.62 call spds, 4.75
Block/screen 11,000 SFRU6 95.93/96.06/96.18/96.31 put condors, 1.5
1,750 SFRM6 96.50/96.56/96.62/96.68 call condors ref 96.35
Treasury Options:
6,300 TYM6 110.5/111/111.25/113 broken call condors
+25,000 wk5 TY 111.5 calls, 8 ref 110-05
2,000 TYM6 109 puts, 8 ref 110-10
20,000 wk2 TY vs. Wed/wkly TY 110/110.25 put spd spds
5,000 TYM6 111/111.5 1x2 call spds
6,000 FVM6 107.25/108 strangles
over 4,000 TYM6 109 puts, 9 ref 110-08
+1,500 USM6 110/111/112/113 put condors, 18 vs. 112-08/0.05%
over 7,000 wk2 TY 110 puts, ref 110-07 (exp 05/08)
-2,000 TYM6 112.25/113 put spds, 46 ref 110-08.5
+2,000 TYM6 110.25/112.25 put spds, 134
MNI FOREX: JPY Remains Currency of Interest; GBP Looks Through Bond Volatility
- JPY was the currency of interest Tuesday, working against last Thursday's intervention-led rally. USD/JPY rallied well at the NY crossover on a surge in volumes, but on very little news. The Tuesday rally is likely to keep overnight vols highly supported for the foreseeable future. Implied vols continue to hit north of 15 vol points for the overnight maturity - and the market's demonstration that it's willing to push back against official intervention should keep this metric supported. The intraday USDJPY rally hit 157.84 before fading, after which the level held well as resistance through the duration of Tuesday trade.
- GBP's resilience continues to standout. Further stress evident in UK bond markets helped push benchmark 30y Gilt yields to the highest levels since the late 1990s, further widening the spread against German bonds as an indicator of relative fiscal weakness. Nonetheless, GBP traded well. GBPUSD rallied to trade back above 1.3550, and recent fresh cycle highs confirm the uptrend to signal scope for an extension towards 1.3701, a Fibonacci retracement.
- Rising tensions with Iran continue to linger, but there has been little sign of a return to open conflict, even as the UAE government issued another missile and drone warning, and as Trump continued to warn Tehran of the consequences of not reaching a deal in an address from the Oval Office. Global equity markets remain resilient, however, with the e-mini S&P again nearing Friday's record highs of 7300.75 - which may embolden Trump's approach as the ceasefire drags on with little sign of a breakthrough in negotiations.
- Focus for the duration of Wednesday trade turns initially to Chinese services and composite PMI data and the ADP Employment Change for April - just ahead of Friday's payrolls print. Central bank speakers include ECB's Cipollone, BoC's Macklem and Fed's Musalem & Goolsbee.
MNI OPTIONS: Expiries for May06 NY cut 1000ET (Source DTCC)
- EUR/USD: $1.1550(E1.5bln), $1.1675(E1.5bln), $1.1775(E675mln), $1.1790-00(E575mln)
- USD/JPY: Y158.00($1.0bln), Y159.15($953mln)
- EUR/JPY: Y183.70-90(E646mln
- AUD/USD: $0.7045-55(A$3.0bln), $0.7200(A$1.1bln), $0.7250(A$1.9bln)
MNI US STOCKS: Late Equities Roundup: New Highs for Nasdaq, Intel & Apple Talk Deal
- US equity indexes trade firm late Tuesday - unwinding yesterday's sell-off with the Nasdaq rising to a new record high of 25358.28, SPX eminis nearing record highs as well - trading around 7296.0 today vs. 7300.75 high yesterday. The DJIA remains supported - just off February's record high of 50512.79.
- Information Technology sector shares led advances in the second half with Intel Corp surging nearly 14% amid reports they are discussing a chipmaking partnership with Apple. Close behind, Sandisk gained over 12% after securing over $42B in AI deals" Benzinga reported.
- Meanwhile, Micron Technology, Akamai Technologies and QUALCOMM gained between 9% to 11% on the day.
- On the flipside, defense contractor Huntington Ingalls Industries declined -12.6% after earning came out in line but forward guidance did not impress. Meanwhile, Financial services Fiserv Inc and PayPal Holdings decline 9-9.25%.
MNI EQUITY TECHS: E-MINI S&P: (M6) Bull Cycle Still In Play
- RES 4: 7347.25 1.500 proj of the Apr 123 - 28 - 29 price swing
- RES 3: 7330.26 1.382 proj of the Apr 123 - 28 - 29 price swing
- RES 2: 7309.23 1.236 proj of the Apr 123 - 28 - 29 price swing
- RES 1: 7300.75 High May1
- PRICE: 7285.25 @ 14:24 BST May 5
- SUP 1: 7131.25 Low Apr 29
- SUP 2: 7078.42 20-day EMA
- SUP 3: 6954.34 50-day EMA
- SUP 4: 6767.00 Low Apr 13
The primary long-term uptrend in S&P E-Minis remains intact and last week’s fresh cycle highs reinforce current conditions. The move higher confirmed a resumption of the primary uptrend. Sights are on 7309.23, a Fibonacci projection. Note that moving average studies are in a bull-mode position, a strong bullish signal that highlights a dominant uptrend. Initial support lies at 7078.42, the 20-day EMA.
MNI COMMODITIES: Crude Falls as Ceasefire Remains Intact, Gold Rises
- Oil prices have fallen today as the US downplayed Iranian attacks on Monday and said the ceasefire is still in effect. This follows the surge in crude yesterday after strikes on the UAE and reports of exchanges of fire between the US and Iran over vessel transits via the Strait of Hormuz.
- WTI Jun 26 is down by 4.3% at $101.9/bbl.
- The UAE issued safety notices and may have been targeted by further attacks on Tuesday. US General Caine said Iran’s attacks yesterday did not pass the threshold of restarting major combat operations.
- The primary bull cycle in WTI remains intact, with last week’s gains reinforcing current trend conditions. The contract previously cleared resistance at $104.34, the Mar 9 high and bull trigger, to confirm a resumption of the uptrend.
- On the downside, initial firm support lies at $98.79, the 20-day EMA, followed by the 50-day EMA at $92.09.
- Meanwhile, spot gold has risen today as broader USD volatility has remained contained, with little sign of a return to open conflict in Iran, despite the lingering tensions.
- Spot gold is up by 0.9% at $4,560/oz.
- From a technical perspective, gold maintains a bearish tone for now and continues to trade below its recent highs. On the upside, a continuation of gains would open $5,000.0.
- For bears, renewed losses would highlight a resumption of the medium-term bear condition and signal scope for a move towards $4,306.4, the Mar 24 low.
WEDNESDAY DATA CALENDAR
| Date | GMT/Local | Impact | Country | Event |
| 06/05/2026 | 0600/0800 | *** |  SE | Flash Inflation Report |
| 06/05/2026 | 0600/0800 | *** | SE | Flash Inflation Report |
| 06/05/2026 | 0645/0845 | * |  FR | Industrial Production |
| 06/05/2026 | 0715/0915 | ** |  ES | S&P Global Services & Composite PMI (f) |
| 06/05/2026 | 0745/0945 | ** |  IT | S&P Global Composite & Services PMI (f) |
| 06/05/2026 | 0750/0950 | ** | FR | S&P Global Composite & Services PMI (f) |
| 06/05/2026 | 0755/0955 | ** |  DE | S&P Global Composite & Services PMI (f) |
| 06/05/2026 | 0800/1000 | ** |  EU | S&P Global Composite & Services PMI (f) |
| 06/05/2026 | 0800/1000 | * | IT | Retail Sales |
| 06/05/2026 | 0800/1000 | EU | ECB Lane Panel on Monpol/Central Bank Independence | |
| 06/05/2026 | 0820/1020 | EU | ECB Cipollone Keynote at Sustainable Development Festival | |
| 06/05/2026 | 0830/0930 | ** |  GB | S&P Global Composite & Services PMI (Final) |
| 06/05/2026 | 0900/1100 | ** | EU | EZ PPI |
| 06/05/2026 | 0900/1000 | * | GB | Index Linked Gilt Outright Auction Result |
| 06/05/2026 | 1100/0700 | ** |  US | MBA Weekly Applications Index |
| 06/05/2026 | 1230/0830 | *** | US | Treasury Quarterly Refunding |
| 06/05/2026 | 1330/0930 | US | St. Louis Fed's Alberto Musalem | |
| 06/05/2026 | 1430/1030 | ** | US | US DOE Petroleum Supply |
| 06/05/2026 | 1430/1030 | ** | US | DOE Weekly Crude Oil Stocks |
| 06/05/2026 | 1700/1300 | US | Chicago Fed's Austan Goolsbee | |
| 06/05/2026 | 2015/1615 |  CA | BOC Governor and Sr Deputy testify at Senate. | |
| 07/05/2026 | - |  NO | NorgesBank Meeting | |
| 07/05/2026 | - | SE | Riksbank Meeting | |
| 06/05/2026 | - |  MX | Banxico Meeting | |
| 07/05/2026 | 0130/1130 | ** |  AU | Trade Balance |


