EQUITIES: Latest Sell-Off Reinforces Bearish EuroStoxx Theme
A clear bear cycle in EuroStoxx 50 futures remains intact and the latest impulsive sell-off reinforces the current bearish theme. The recent breach of both the 20- and 50- day EMAs highlighted a stronger reversal. Sights are on the next key support at 5500.00, the Nov 21 ‘25 low. A clear break of this level would strengthen the bear cycle. Initial firm resistance is at 5833.00, the Mar 6 high. S&P E-Minis have traded sharply lower today as the contract begins the week on a bearish note. The break of 6751.50, the Feb 6 low, confirms a range breakout and highlights a stronger short-term reversal. Sights are on 6583.00, the Nov 21 ‘25 low and a key medium-term support. A clear breach of this level would strengthen the bear theme and open 6534.52, a Fibonacci projection. Initial firm resistance is 6751.50, the Feb 6 low.
- Japan's NIKKEI closed lower by 2892.12 pts or -5.2% at 52728.72 and the TOPIX ended 141.09 pts lower or -3.8% at 3575.84.
- Elsewhere, in China the SHANGHAI closed lower by 27.591 pts or -0.67% at 4096.603 and the HANG SENG ended 348.83 pts lower or -1.35% at 25408.46.
- Across Europe, Germany's DAX trades lower by 567.72 pts or -2.41% at 23021.56, FTSE 100 lower by 181.87 pts or -1.77% at 10103.13, CAC 40 down 195.7 pts or -2.45% at 7797.79 and Euro Stoxx 50 down 151.05 pts or -2.64% at 5568.85.
- Dow Jones mini down 597 pts or -1.26% at 46932, S&P 500 mini down 72 pts or -1.07% at 6672.75, NASDAQ mini down 292.25 pts or -1.18% at 24383.5.
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
AUSSIE 10-YEAR TECHS: (H6) Found Bottom?
- RES 3: 95.982 - 76.4% retracement Sep’24 - Nov’24 downleg
- RES 2: 95.960 - High Apr 7 (cont.)
- RES 1: 95.900 - High Oct 17
- PRICE: 95.125 @ 16:19 GMT Feb 06
- SUP 1: 95.075 - 2.0% Lower Bollinger Band
- SUP 2: 95.030 - Low Jan 28
- SUP 3: 94.190 - 1.0% 10-dma envelope
Aussie 10-yr futures remain under pressure, although the CPI print has helped alleviate some of the worst of the pressures. adding to the downside argument. This puts prices still south of all major support levels. With 95.275 cleared, prices are pushing to new contract lows, opening vol-band support through 95.075 and into 94.190. Any recoveries need to break back above 95.900 to signal near-term bullish traction.
MACRO ANALYSIS: MNI US Macro Weekly: Soft Labor Surprises Precede Payrolls
We've just published our US macro weekly: Download Full Report Here
- January’s Employment Report may have been pushed back to Feb 10 due to the brief federal government shutdown, but in the meantime there was plenty of labor market data to chew on this week.
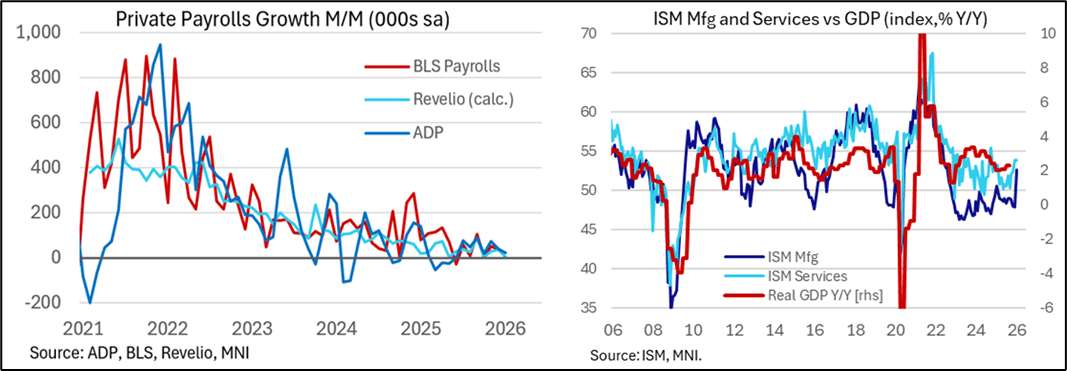
- Most of it was weaker than expected, including ADP payrolls and Revelio Labs payrolls, Challenger job cuts and hiring announcements, JOLTS job openings, and the latest weekly initial jobless claims.
- There are mitigating explanations (JOLTS doesn’t line up with private sector estimates so may bounce in January; jobless claims look impacted by severe weather), but overall theme of a lower hiring and lower firing (with the exception of the Challenger data) labor market easily remains intact.
- That remains in divergence with the continued solidity in the latest activity data, with ISM Manufacturing soaring (highest since Aug 2022) and Services putting in another solid print (joint-15 month high).
- The flawed UMichigan survey suggested that consumer sentiment has bottomed, while the latest credit indicators appeared to show slight acceleration. Latest retail sales metrics are solid if somewhat mixed.
- Rate markets largely tracked the bifurcation in data. Strong ISMs saw Fed easing potential fade early in the week, but there was a reversal in a more dovish direction by week-end alongside the soft labor data and tech-led equity weakness exacerbating negative risk sentiment.
- Fed Funds futures at one point implied 63bp of cuts to end-2026. That has since pulled back closer to 55bp with some stabilization in risk assets and a subsequent boost from U.Mich consumer sentiment firming.
- FOMC speakers were mostly patient on the next move, including increasingly cautious-sounding Board members Cook and Jefferson, with non-voter Daly one of the few flying the dovish flag.
- In general there’s a sense that the economy is resilient with downside labor market risks in relative check, with more evidence required that inflation is converging to 2% before declaring victory on inflation.
- We’ll all be watching the two major releases next week with January reports for nonfarm payrolls (Wed) and CPI (Fri), with Retail Sales on Tuesday also bearing watching (but it’s only for December).
- Monthly payrolls growth is currently expected at 70k in January for a slight acceleration from the 50k in December. The market likely currently views that to be on the high side considering a swathe of soft labor indicators this past week. The unemployment rate will again be a key component in shaping reaction to the report, with consensus currently looking for 4.4% after the 4.38% in December.
- As for CPI inflation, January is always an important month as it begins to capture start-of-year price resets - historically about 20% net price increases for the year come in January and another 20% in February. Consensus currently stands at 0.3% M/M for both headline and core CPI in the early days for the Bloomberg survey.
EUROPEAN INFLATION: MNI Eurozone Inflation Insight: January 2026
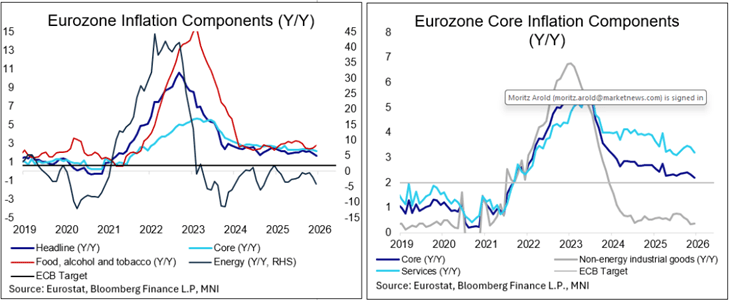
We've published our Eurozone Inflation Insight for the January 2026 flash round - CLICK HERE FOR FULL REPORT
Executive Summary - Services Y/Y Lower But Drivers Ambiguous
- HICP inflation decelerated in January, closely in line with initial analyst consensus. Core HICP also closely in line with expectations.
- Services decelerated more substantially than anticipated on the yearly rate. Details from some countries point towards slower annual repricing behind some of the move but seasonally-adjusted data makes the print look quite firm.
- The full January release on Feb 25 will provide an update on exact drivers, especially on services.
- By country, trends were mixed: Germany, Italy and Spain surprised to the upside while France was lower than expected.
- Methodology updates in January only brought material changes to processed and unprocessed foods categories.
- Ongoing rhetoric suggests the ECB Governing Council thinks the bar to a move into either direction is high.