ECB: Lagarde: Right To Characterise Today As A No Hiking Decision
Oct-29 14:25
Q: "I would like to know if this no hiking thing because of tighter financial conditions in the mark...
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
SOFR OPTIONS: Midmorning SOFR Options Summary
Sep-29 14:24
Morning flow appears mixed amid rising volumes. Underlying futures weaker - but off lows following JOLTS and Consumer Confidence data. Current rate hike projections vs. late Monday levels (*): Oct'26 at +16.8bp (+16.9bp), Dec'26 +37.3bp (+38.2bp), Jan'27 +51.4bp (+50.4bp), Mar'27 +69.8bp (+70bp).
- Block, 8,000 SFRU7 94.75/95.00 call spds, 15.25 vs. 95.08/0.10%
- 9,400 SFRX6 95.75/95.81/95.87/95.93 call condors
- +2,000 SFRZ6 95.6875/95.875/96.0625 call flys 3.25 ref 95.61
- -3,000 SFRH7 94.25/96.25 strangles, 6.0 95.305
- +5,000 SFRZ6 95.37/95.56/95.62 put trees, 1.75 ref 95.61
- +2,500 SFRH8 93.50/96.50 call over risk reversal, 0.0 ref 95.12
- +10,000 SFRM7 96.62/97.37 2x3 call spds, 2.25 ref 95.14
- +1,500 SFRM8 95.00 straddles, 116.5 vs. 95.135/0.06%
- +20,000 SFRU7 94.75/95.00 call spds, 15.25-15.0 ref 95.09 to -.06
- +2,000 SFRM7 95.50/95.87/96.00/96.31 3x6x2x4 call condors, +0.0-.25 ref 95.145
- +5,000 SFRZ7 96.25/97.00 call spds, 7.0 ref 95.11
- -4,000 SFRH7 95.93 puts, 60.5 ref 95.32
ECB: Lower Levels Of Excess Liquidity Starting To Make Its Mark
Sep-29 14:21
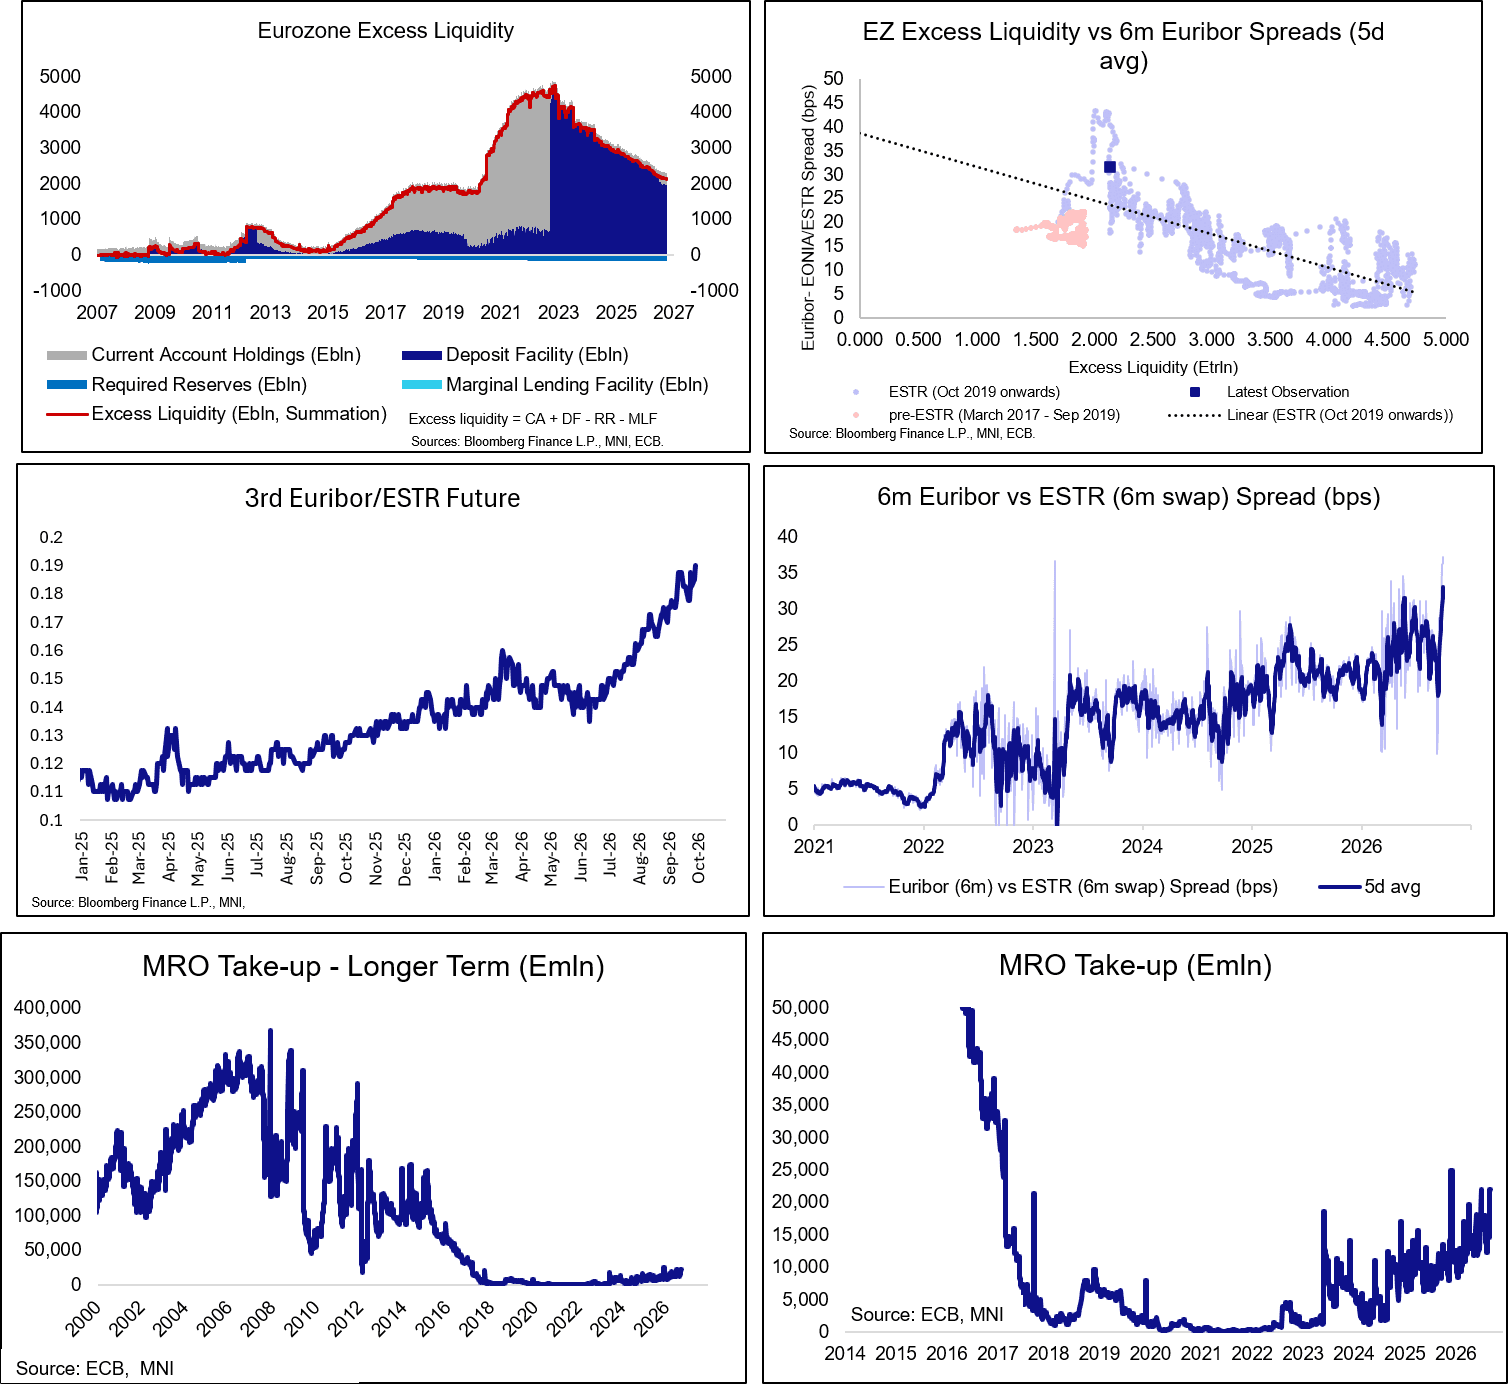
Eurozone excess liquidity is currently just over E2.115trln, down from E2.457trln at the start of the year. Balance sheet run-off has been orderly thus far, but lower levels of excess liquidity are being reflected in some money market spreads and liquidity operation take-up,
- Take-up at today’s MRO operation was E21.9bln, a similar amount to that seen at July month-end. For context, take-up around year-end 2025 was ~E25bln. Total usage remains extremely low relative to pre-2018 levels.
- Ahead of September month- and quarter-end, the 6m Euribor/ESTR spread has risen to a fresh high on a one-day (37bp) and 5-day MA (33bp) basis.
- In late June, Reuters sources noted that the ECB was considering raising minimum reserves from 1% of eligible deposits to 2%. Required reserves are currently ~E175bln, so a doubling of the requirement ratio would reduce Eurozone excess liquidity by a commensurate amount.
- Markets have been positioning for a lower excess liquidity regime via Euribor/ESTR futures. Since June, the M7 future has risen from under 15.0 ticks to 19.0 ticks at present. With current markets division head Schnabel set to leave the ECB at the start of next year, there may be growing expectations of an update on MRR and the balance sheet more broadly in the coming months.
- In an interview with Reuters this month, Vice President Vujcic noted that “I have always viewed reserve requirements as a straightforward way to sterilise part of the excess liquidity. I would rather sterilise excess liquidity than charge fees and tiering is quite complicated”
STIR: Euribor - Flattening the strip
Sep-29 14:18
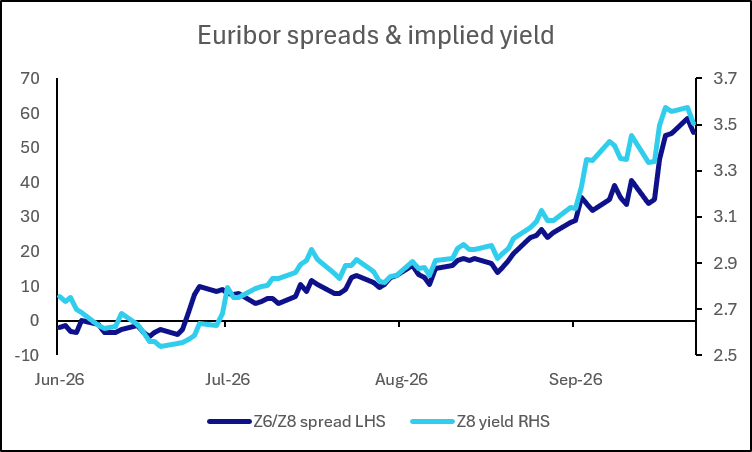
- Back-end Euribor contracts are leading today’s rise, while the whites lag the broader move. The ERZ6/Z8 spread has edged down slightly from yesterday’s highs and is hovering around 54bp.
- The correlation with Z8 implied yields continues to display the strong positive directionality seen in recent months, reflecting the broader macro shift toward pricing higher structural rates at the back end of the curve.
Related bullets

Related by topic
EUR/USD
Bunds
Germany
Euribor
European Central Bank


