IRAN: "IRAN'S FOREIGN MINISTER TELLS SAUDI COUNTERPART TEHRAN IS READY [...]
"IRAN'S FOREIGN MINISTER TELLS SAUDI COUNTERPART TEHRAN IS READY TO PROVIDE ASSISTANCE TO FACILITATE...
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
US INFLATION: MNI US Inflation Insight: Firm Core Prices Seal Deal For Hike
We've published our review of the August inflation round - Download Full Report Here
- While August’s inflation data didn’t show a major acceleration in underlying pressures, nor will they have offered comfort to Fed participants who are looking for more decisive indications of progress toward the 2% target.
- Core CPI rose 0.29% M/M, above the 0.22% consensus and July’s 0.22%. The upside surprise was driven by supercore inflation, with core goods coming in on the soft side of expectations.
- Headline CPI was broadly in line with consensus. The monthly acceleration reflected a rebound in energy prices, while food inflation remained relatively tame. Grocery prices were flat, but food away from home remained on the warm side and indicative of continued service-sector price pressures.
- The main upside drivers in core were arguably outliers: a record increase in wireless telephone services, a rebound in lodging, and less-negative car insurance. Housing was softer than expected, while medical services were relatively benign.
- Some aspects were somewhat less concerning than the core reading suggested: median and trimmed-mean measures were softer, while dispersion measures showed some moderately encouraging developments.
- However, inflation remained broad and elevated by pre-pandemic standards, and supercore trends picked up from softer prior readings.
- The PPI report showed more moderate pipeline pressures compared to July, but run rates remained elevated amid continued energy passthrough. PCE-relevant components—including airfares and parts of healthcare -- looked on the firm side.
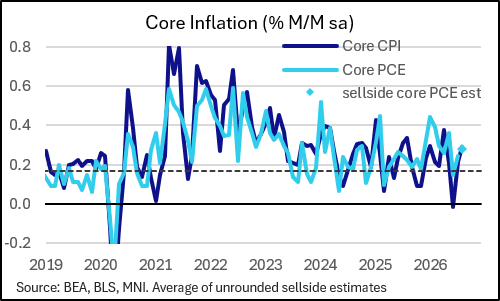
- As a result, core PCE tracking moved into the 0.25–0.30% M/M area (vs 0.21-0.22% coming into the inflation round), with consensus clustered in the high 0.20s. That would translate roughly into a 2.7-2.8% core PCE run rate on a 3-month annualized basis, with Y/Y continuing to run well above 3%.
- Gov Warsh and most of the FOMC are unlikely to be convinced that this represents anything close to a resumption of disinflationary progress. Accordingly, the data were enough to see market-implied pricing for a September Fed hike firm to well over 80%, from under 60% prior to PPI.
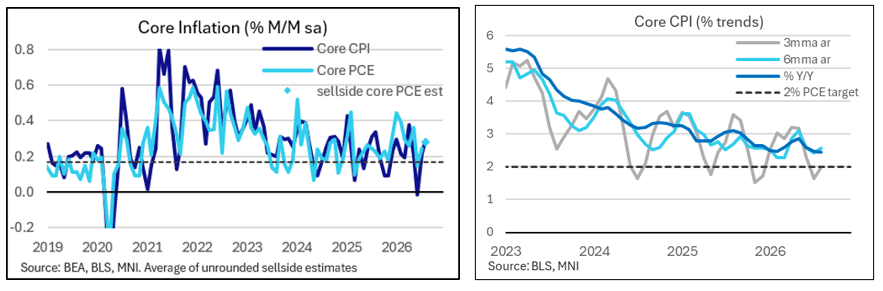
US DATA: Core PCE Tracking In 0.25-0.30% Area
Analyst estimates for August core PCE picked up again after Friday's CPI data. Prior to the release, an early median of analysts had seen core PCE at 0.24-0.25% M/M, similar to 0.25% in July; it had been around 0.21-0.22% pre-PPI; consensus now appears to be clustered in the high 0.20s.
- Barclays: 0.25% (was 0.22% pre-CPI, 0.23% pre-PPI)
- Goldman Sachs: 0.26% (0.24% pre-CPI, was 00.22% pre-PPI)
- Nomura: 0.278% (0.245% pre-CPI, was 0.205% pre-PPI).
- BofA: 0.30% (was 0.26% pre-CPI, 0.24% pre-PPI)
- TD: 0.32% (0.24% pre-CPI, was 0.18% pre-PPI)
- Mizuho: 0.3% (under old methodology and 0.4% under new methodology)
USDCAD TECHS: Bearish Theme
- RES 4: 1.4175 High Jul 13
- RES 3: 1.4129 High Jul 28
- RES 2: 1.4080 High Aug 4 and 5
- RES 1: 1.3917/3940 50-day EMA / High Sep 2
- PRICE: 1.3872 @ 16:32 BST Sep 11
- SUP 1: 1.3732 Low Aug 21 and the bear trigger
- SUP 2: 1.3715 76.4% retracement of the May 1 - Jun 24 bull cycle
- SUP 3: 1.3672 Low May 12
- SUP 4: 1.3620 Low May 7
The trend in USDCAD remains bearish. The reversal on Sep 2 reinforces a bear theme and the move down leaves a key near-term resistance at the 50-day EMA, at 1.3917, intact. A clear break of this average is required to strengthen any short-term bull theme and this would signal scope for a stronger retracement of the Jun 24 - Aug 21 bear leg. For bears, attention is on key near-term support at 1.3732, the Aug 21 low.


