US IG HEALTHCARE: IG Healthcare: Week In Review
Spreads moved sideways ending the week at +68, on a quiet week with no new issuance....
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
US TSYS: Slightly Richer After Yesterday's Subdued Summer Session
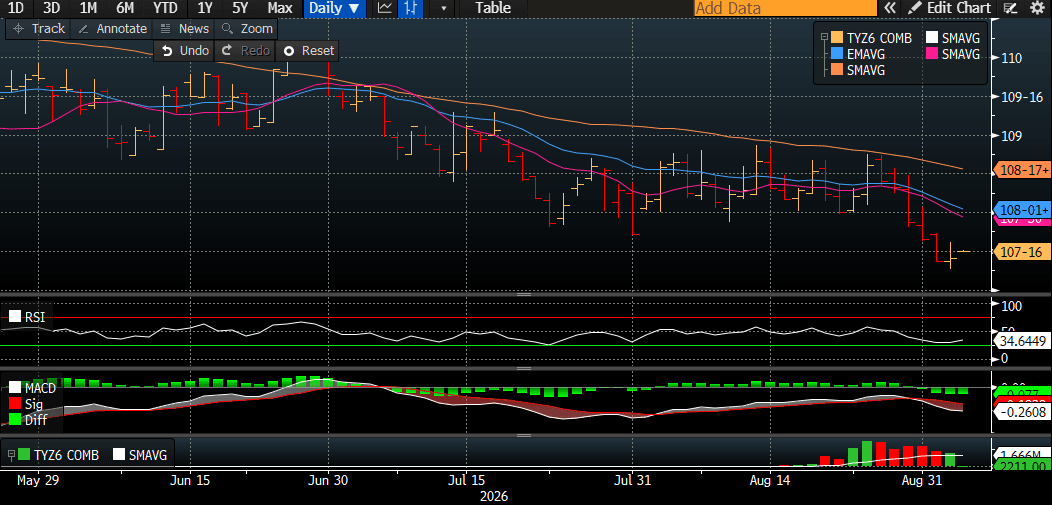
TYZ6 is dealing at 107-16, +0-03 from closing levels in today’s Asia-Pac session.
- Cash bonds finished yesterday’s session 2-3bps richer.
- Little to no reaction to the latest Fed Beige Book release.
- Generally quiet late summer trade with moves reportedly based on Saudi plea for US/Iran to deescalate, US officials expressing optimism over controlling tensions.
- Projected rate hike pricing cool slightly vs. late Tuesday levels (*): Sep'26 at +16.2bp (+17bp), Oct'26 at +23.2bp (+24.3bp), Dec'26 38.2bp (+39.5bp), Jan'27 44.4bp (45.8bp).
- MNI Techs (TYZ6): Trend needle in Treasuries continues to point south and a fresh cycle low this week reinforces bearish conditions. Note that moving averages are in a bear-mode position too, highlighting a dominant downtrend. Support at 107-22+, the Jul 31 low, has been cleared. Sights are on 107-02+ next, a Fibonacci projection. Key resistance to watch is at the 50-day EMA, currently at 108-18.
Bloomberg Finance LP
BONDS: NZGBS: Little Changed After Yesterday's Subdued NY Session
NZGBs are 1bp cheaper after US tsys finished yesterday’s session 2-3bps richer.
- Generally quiet late summer trade with moves reportedly based on Saudi plea for US/Iran to deescalate, US officials expressing optimism over controlling tensions. Little to no reaction to the latest Fed Beige Book release.
- Terms of trade fell 9.0% q/q (estimate -1.9%) in Q2 versus revised -1.9% in Q1.
- (Bloomberg) - "RBNZ's Breman Expects Core Inflation to Increase Further. Says core inflation rose to 2.7% in 2q and is expected to be higher as indirect impacts of fuel shock are measured. Says gradual removal of monetary stimulus is appropriate. MPC can probably take some time to assess and see how the two OCR hikes so far have affected the economy."
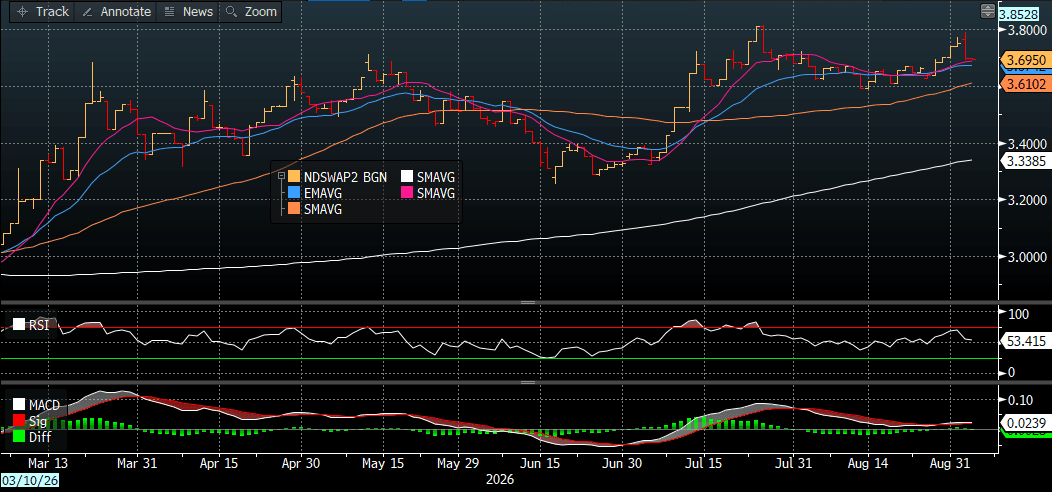
- Swap rates are 1bp higher, with the 2-year rate at 3.70%. Our 4.0% target is looking achievable again now that the paring in the expected peak has reversed. The 2-year swap rate has historically peaked around 50bps above the eventual OCR peak across previous tightening cycles.
- RBNZ-dated OIS pricing is slightly firmer across meetings. 8bps of tightening is priced for October, while February 2027 assigns 38bps.
- The local calendar will also see ANZ Commodity Price data.
- Today, the NZ Treasury plans to sell NZ$275mn of the 4.50% May-30 bond and NZ$175mn of the 2.75% Apr-37 bond.
Bloomberg Finance LP
CNH: USD/CNH Back Sub 6.7200 But Still Above Aug Lows, Services PMI Today
Spot USD/CNH tracks at 6.7175 in early Thursday dealings, close to 100pips sub Wednesday intra-session highs as broader USD sentiment faltered as Wednesday's session unfolded. The BBDXY index finished off close to 0.20%, as oil prices retreated sharply from intra session highs (with a Saudi plea for US/Iran to deescalate impacting). UST yields retreated which also weighed on the USD (with yen gains notable as well). For USD/CNH we continue to maintain a low beta with respect to these broader shifts and the pair hasn't made a fresh low since Aug 24. Downside focus will remain on a test towards 6.7000 (with early 2023 cycle lows at 6.6975). The 20-day EMA continues to track lower and now offers resistance near the 6.7310 level.
- Spot USD/CNY finished up yesterday 6.7192, while the CNY CFETS basket tracker rose further to 101.99 (up 0.16%). The index has been recovering the past week amidst higher USD index levels, but this may now pause given yuan's low beta to weaker USD episodes.
- PBOC Governor Pan stated at the G20 that China doesn't need to depreciate the yuan for trade gains. Via BBG: "The People’s Bank of China’s Governor Pan Gongsheng said China has no need or intention to gain a trade advantage through currency depreciation, the state-run Securities Times reports, citing his comments at the G20 meetings." This comes after US Tsy Secretary Bessent stated yesterday China dissented on a joint G20 statement around the unsustainability of cheap exports.
- Earlier headlines crossed that US President Trump is planning a state dinner for China President Xi's trip to the US later in Sep. Market expectations for a major break through from the trip around US-China trade tensions/tariff levels is fairly low at this stage.
- On the data front today we have Aug RatingDog services PMI. The market consensus is for a 50.6 outcome, prior was 50.4.


