FED FUNDS FUTURES: FFF7 Bought
FFF7 ~7.1K crosses at 95.855 over a couple of clips, initially buyer-driven....
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
UK FISCAL: PSNBex Broadly In Line; Lower Cash Borrowing Could Impact Gilt Remit
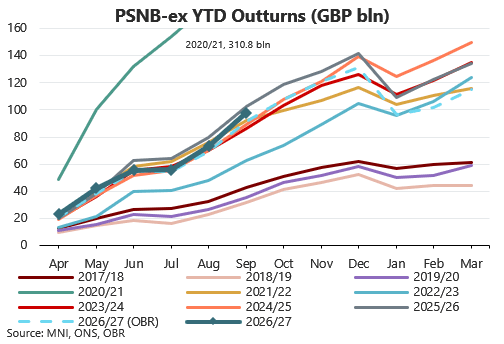
PSNB-ex came in at GBP24.52bln in September (24.0bln cons, 22.6bln OBR), broadly in line with consensus and a touch above the OBR's forecast. Although, coupled with fiscal year-to-date downward revisions of GBP3.98bln, this takes the YTD borrowing figure up to GBP97.84bln, now GBP6.0bln above the OBR's forecast, narrower than the GBP8.1bln gap to forecast realised in initial August data.
- While this does improve the fiscal tracking picture slightly compared to what we saw in August data, the final figures here may not fully impact next week's Budget and accompanying OBR forecasts (both due Wednesday 28 October), as the cut off for inputs was likely passed some time ago. However, as the OBR has access to some non-public data to make their forecasts, there could be elements that are incorporated.
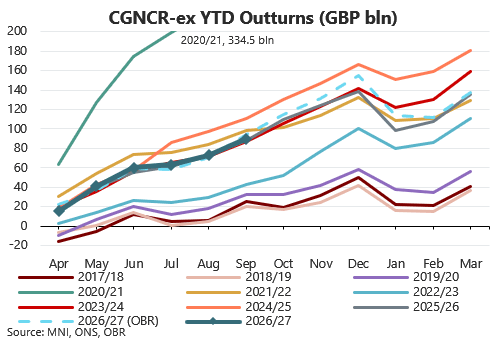
- On a cash basis (which are hugely important for the gilt remit at this juncture) the picture for public finances improved more markedly. September CGNCR-ex came in at GBP16.91bln, well below the OBR's GBP24.2bln forecast. This takes the YTD figure up to GBP90.03bln, now GBP4.3bln below the OBR's forecast (down from a GBP+2.8bln gap realised in initial August data). These latest numbers are very likely to be taken by the DMO as part of its remit revision, and could therefore reduce expectations of an in-year increase to gilt issuance for FY26/27.
- Turning to the September PSNB (accruals) data, central govt current receipts rose to GBP554.25bln YTD, now GBP5.8bln above the OBR's forecast, notably larger than the GBP1.1bln gap realised in initial August data. The receipts figure is GBP31.56bln higher than this time last year.
- Within this, the improvement remains driven by stronger income tax receipts (GBP2.9bln above OBR fcst vs GBP1.9bln gap in August, pre-revisions), entirely on PAYE (GBP5.2bln above forecast vs GBP3.9bln Aug), alongside NICs (GBP2.0bln above forecast vs GBP1.8bln Aug).
- VAT receipts remain just below forecast YTD (after having dropped to a negative forecast error last month), now GBP0.7bln below the OBR's forecast, although slightly improved from the GBP-0.9bln gap in August. Self-assessed income tax also remained tracking around GBP0.2bln below forecast, so a very marginal hit there.
- On the spending side, central govt current expenditures rose to GBP656.94bln YTD, now GBP8.9bln above the OBR's forecast, wider than the GBP7.4bln we saw in August. The figure is GBP30.83bln higher than this time a year ago.
- Within expenditures, there is a notable above-forecast rise in interest payments which are now GBP3.8bln above forecast, up from the GBP2.0bln gap in August (which in turn had widened from GBP1.0bln July) - making it a key driver of the worsening expenditure picture. Elsewhere, the other drivers of the overshoot remain broadly unchanged in comparison, net social benefits tracking GBP2.5bln above forecast (GBP2.5bln Aug), net investment GBP1.8bln above forecast (GBP2.5bln Aug), and to a lesser extent subsidies GBP0.8bln higher (GBP0.5bln Aug).
- On the revisions through FY2026/27 so far, the GBP3.98bln downward revision to PSNB-ex between Apr-Aug is mostly concentrated in Jul-Aug (Jul rev down GBP1.67bln, Aug rev down GBP1.02bln). Revisions were revenue-led. Across the fiscal year so far, central govt receipts were revised up GBP3.47bln, and expenditures down GBP0.67bln.
SILVER TECHS: Still Looking For Weakness
- RES 4: $74.131 - High Jun 5
- RES 3: $72.076 - 50.0% retracement of the May 13 - Jul 17 bear leg
- RES 2: $71.142 - High Aug 28 and the bull trigger
- RES 1: $62.060/67.546 - 50-day EMA / High Sep 22
- PRICE: $57.326 @ 08:29 BST Oct 21
- SUP 1: $55.401 - Low Oct 14
- SUP 2: $54.778 - Low Jul 17 and bear trigger
- SUP 3: $52.577 - 1.000 proj of the Mar 2 - 23 - May 13 price swing
- SUP 4: $50.000 - Psychological round number
Silver is unchanged. A bear cycle remains intact. A sharp sell-off and a fresh cycle low on Oct 14, reinforces current conditions. The move down confirms a resumption of the bear leg that started on Aug 28. Sights are on $54.778, the Jul 17 low and a bear trigger. Clearance of this level would confirm a resumption of the medium-term downtrend. Key resistance has been defined at $71.142, the Aug 28 high.
USDCAD TECHS: Has Breached The 50-Day EMA
- RES 4: 1.4432 2.000 proj of the Jan 30 - Mar 31 - May 1 price swing
- RES 3: 1.4415 High Apr 01 ‘25
- RES 2: 1.4328 1.764 proj of the Jan 30 - Mar 31 - May 1 price swing
- RES 1: 1.4151/4300 20-day EMA / High Oct 14 and bull trigger
- PRICE: 1.4057 @ 08:25 BST Oct 21
- SUP 1: 1.4032 Low Oct 20
- SUP 2: 1.4016 50.0% retracement of the Aug 21 - Oct 14 bull cycle
- SUP 3: 1.3974 Low Sep 17
- SUP 4: 1.3949 61.8% retracement of the Aug 21 - Oct 14 bull cycle
The short-term bear leg in USDCAD remains intact. Tuesday’s extension resulted in a breach of support around the 50-day EMA at 1.4076. A clear break of the average would signal scope for a deeper retracement and open 1.4016 initially, a Fibonacci retracement point. The move down appears corrective for now. Key resistance and the bull trigger has been defined at 1.4300, the Oct 14 high.


