OPTIONS: Expiries for Sep14 NY cut 1000ET (Source DTCC)
Sep-11 15:04
* EUR/USD: $1.1580(E630mln), $1.1600(E1.2bln), $1.1620-25(E2.0bln), $1.1645(E575mln), $1.1700(E1.0...
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
US TSY FUTURES: BLOCK: Sep'26 5Y Sale
Aug-12 15:01
- -7,000 FVU6 106-13.5, sell through 106-13.75 post time bid at 1054:00ET, DV01 $294,000
- The 5Y contract trades 106-13 last (+2.75)
GILTS: Wider Cues Still Eyed
Aug-12 14:57
Futures have pulled back from this morning’s highs, with wider cross-market swings dominating and in line U.S. CPI data providing little impetus.
- Wider macro headline flow has been a little limited during the London afternoon, leaving yields within 1bp of yesterday’s closing level with a light twist steepening bias.
- Futures last -11 at 87.13. The recovery between Jul 23-Aug 5 is considered corrective and represents a retracement of the Jun 25-Jul 23 bear leg. A resumption of gains would signal scope for move towards 88.48, a Fibonacci retracement. However, the latest move down signals the potential end of the corrective bounce and sights are on key support at 85.77, the Jul 23 low and bear trigger.
US DATA: Continued Hotel CPI Pullback Helps Offset Higher Medical Care Services
Aug-12 14:46
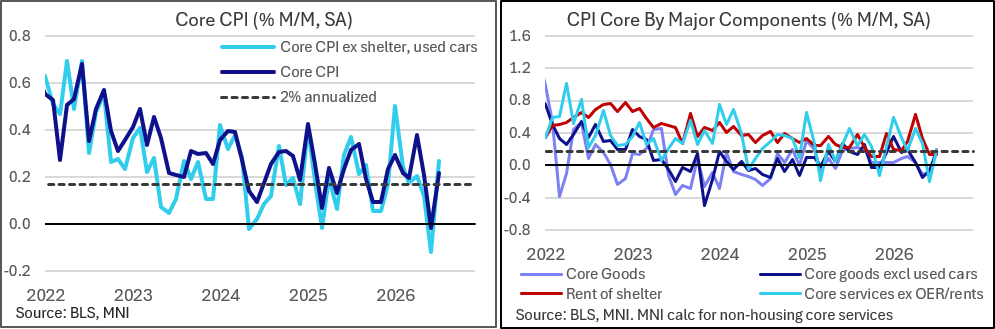
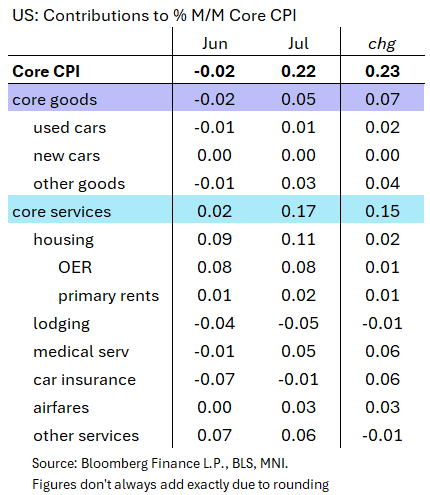
The swing in core CPI from -0.02% M/M in June to 0.22% in July came largely on the back of higher core services prices, though the pickup in core goods prices was also notable - see table in image below.
- Core goods (which rose 0.20% M/M, -0.09% prior) contributed 0.05pp to core CPI in July, up from -0.02pp in June, with vehicle prices and "other" goods contributing positively vs flat/negative in June as discussed earlier.
- Core goods ex-used vehicles rose at a 0.16% M/M rate, fastest in 4 months. In "other goods", soft medical care goods (-0.6%, in turn dragged down by both drug and equipment deflation), was offset by still-elevated recreational commodities (+0.6%) along with the previously mentioned rise in consumer electronics prices and apparel.
- In core services, which contributed the remaining 0.17pp to core CPI in July (up 0.23% M/M, 0.03% prior), it was as usual housing that made the biggest single contribution (0.11pp, vs 0.09pp prior).
- A pickup in auto insurance (-0.01pp contribution vs -0.07pp prior) was one of the biggest "swing" contributors to July core CPI, even with the -0.29% (-2.01% prior) M/M representing the 6th month in 7 of declines for this category. Core PCE takes this reading from the PPI report and not CPI however.
- This came alongside stronger medical services price pressures (contributing 0.06pp vs -0.01pp prior). The 0.56% M/M rise in compared with the -0.12% prior and was the 2nd strongest in 12 months and looked quite broad-based, with professional services up 0.4% and hospital / other services up 0.5%. However, most medical care services for PCE purposes come from PPI.
- Conversely, lodging continued to drag on overall inflation for a 2nd month (-0.05pp after -0.04pp) though airfares (which come from PPI for PCE purposes) were a little stronger (+0.03pp after flat) in picking up after June's slowdown to a 7-month low 0.21% M/M (2.22% in July).
- July's -2.75% M/M (-2.32% prior) drop in lodging has been exceeded only once in the last 34 months and potentially reflects some continued giveback from World Cup-related rises.
- A final note: when stripping out used cars and shelter (which includes lodging as well as housing), core CPI rose 0.27% M/M, fastest since January.