EUR: EUR/USD - Treads Water On 1.12 Handle, Sellers Reluctant To Re-Engage
The EUR/USD range overnight was 1.1214-1.1241, Asia is currently trading around 1.1235, +0.02%. The ...
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
US STOCKS: S&P - Risk Shrugs Off Headwinds & Surges Higher, All-Time Highs Next
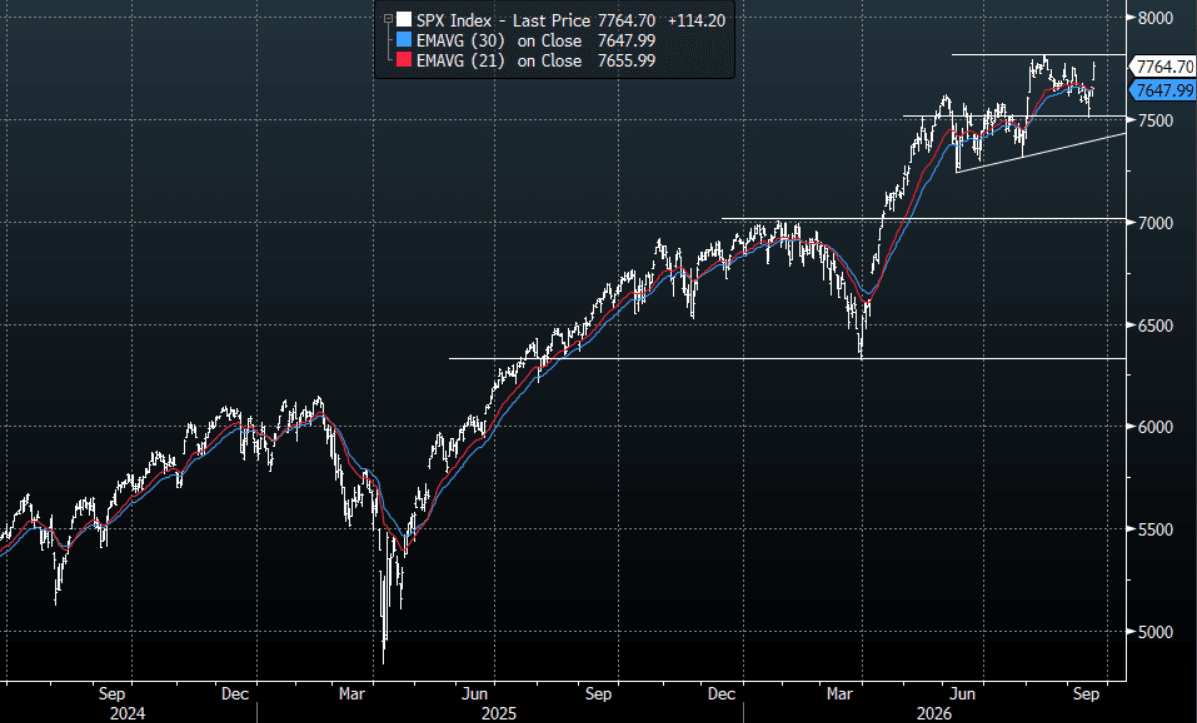
The S&P(ESZ6) range overnight was 7746.00 - 7847.25, SPX closed +1.49%%, Asia is currently trading around 7836. Risk surged higher overnight as early signs of success for Meta’s new AI agent saw buyers scramble to get back into the trade. Oil collapsed on hopes of diplomacy on the sidelines of this week's UN summit. I continue to scratch my head as to how raising rates in a global oil shortage is a positive for growth or risk. Especially with the rhetoric coming out of Europe and Russia and no sign of the impasse at the Straits of Hormuz coming to an end anytime soon. For now though risk is able to ignore any headwinds and trades like a ball being held underwater. On the day, focus will now turn toward the year's highs as the market looks to regain upward momentum heading into month and quarter end.
- Andreas Steno Larsen on X: “A lot of people are bearish into this rally.. A LOT!”
- EndGame Macro on X: "This is happening while diesel prices are surging, monetary policy remains restrictive and large parts of the economy are already showing late cycle stress. The old line about markets remaining irrational longer than investors can remain solvent feels unusually appropriate right now.”
- “The S&P 500 rose the most since early August as semiconductors led by AMD and Intel soared amid signs of success for Meta’s new AI agent Muse.” - BBG
- The S&P 500 Index Average True Range(ATR) for the last 10 Trading days: 80 Points
Fig 1: S&P 500(SPX) Index Daily Chart
Source: MNI - Market News/Bloomberg Finance L.P
NEW ZEALAND: "*NZ'S WILLIS: FUTURE RBNZ POLICY MISTAKES ARE FAR LESS LIKELY
"*NZ'S WILLIS: FUTURE RBNZ POLICY MISTAKES ARE FAR LESS LIKELY
*NZ FINANCE MINISTER NICOLA WILLIS SPEAKS AT NEWS CONFERENCE
"*NZ'S WILLIS: STRONGER GUARDRAILS ARE NOW IN PLACE FOR RBNZ" - BBG"
"*RBNZ REVIEW URGES PUTTING MORE EMPHASIS ON REAL INTEREST RATE
*NZ RELEASES REVIEW OF MONETARY POLICY RESPONSE TO PANDEMIC" - BBG
US TSYS: Futures Supported With Oil Dip, Japan Remains Out, Busier US Data Day
US Tsy futures have opened with a modestly firmer bias in early Tuesday dealings. We were last 106-04, +02+, for the TYZ6, with dips under 106 still generating support. Market focus overnight was firmly on oil price shifts/geopolitical hopes. Oil benchmarks fell over 3% driven by hopes that diplomacy on the sidelines of this week's UN summit will result in safer passage of energy shipments from the Middle East. WTI futures are little changed in the first part of trade today. US Tsy benchmark yields were flat to 4.5ps lower in Monday trade, led by the back end. The 10yr ending around 4.95%. Note Japan markets remain out today, returning on Thursday.
- Overnight, Fed commentary was mixed, with near-term rate hike probabilities virtually unchanged on the day (14bp priced through Oct, 33bp through Dec). St Louis's Musalem, one of the FOMC's most hawkish members, told Reuters that he eyed "further policy restraint"...earlier and incremental policy firming is better and less disruptive than later and larger and potentially more abrupt policy action". More dovishly, Chicago's Goolsbee commented that "I remain relatively optimistic" on getting inflation back to the 2% target.
- One interesting contrast that indicated relative comfort in making further hikes: Musalem suggested that the labor market did not necessarily need to slow in order for inflation to return to target, but Goolsbee warned that monetary tightening "won't be painless".
- The data and Fed speaker schedule gets a little busier Tuesday, with regional Fed activity reports (Richmond, Philly), weekly ADP payrolls, and the US Treasury Market Conference bringing appearances by NY's Williams, SOMA manager Perli, and Gov Jefferson (separately we hear from Richmond's Barkin). Additionally, Treasury sells $69B in 2Y Note at auction.


