FOREX: EURUSD Analyst Views
Mar-04 15:47
- *Natixis believe the recent EUR/USD sell-off has taken place in an exceptionally stressful macro and geopolitical environment. They believe this sharp, fear-driven decline presents a tactical opportunity. While the euro has been badly shaken, we see the dollar's strength as increasingly cyclical and crisis-driven rather than structural. Natixis forecast a progressive EUR/USD recovery towards 1.20 by year-end and propose a EUR/USD call reverse knock-out to play the rebound.
- *ING: The terms of trade story will be the far more important theme and the duration of this energy shock will determine whether EUR/USD needs to trade down to 1.10/12 or can find support near 1.15. ING’s base case is the latter, in which we would expect operational intensity to decrease over the next week and the Straits of Hormuz to slowly reopen.
- *CIBC: The energy price spike remains problematic for the Eurozone and absent a close above the 200Day MAV, currently 1.1671, CIBC would remain mindful of EUR/USD correcting back towards strong support in line with the 5 November low at 1.1469.
- *BBVA: What happens with oil and gas will be key for the EURUSD. If they cannot flow through Hormuz, we will see the EURUSD fall below 1.15. If the situation is finally resolved, current levels are good entry points for long positions.
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
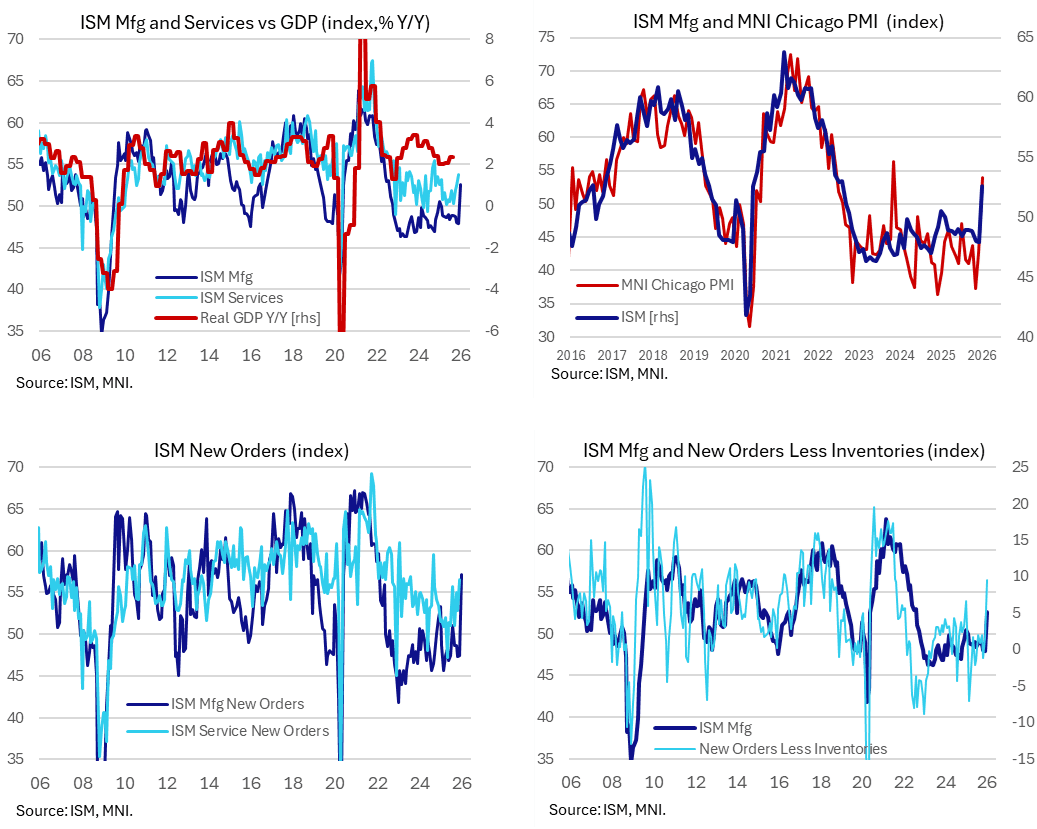
US DATA: ISM Manufacturing Follows MNI Chicago PMI With A Sharp Increase
Feb-02 15:46
The ISM manufacturing report was far stronger than expected in January as it jumped 4.7pts to 52.6 for its highest since Aug 2022, significantly above even the highest analyst estimate of 51.0. New orders and production both surged to their highest since early 2022 - unlike the final PMI survey released shortly beforehand, it doesn’t look linked to an inventory build. The report chimes with a particularly strong MNI Chicago PMI released last week with added support from most of the regional Fed manufacturing surveys also improving in January.
- ISM mfg: 52.4 (cons 48.5, range 47.9-51.0) in Jan after 47.9 in Dec – highest since Aug 2022
- New orders: 57.1 in Jan after 47.7 in Dec – highest since Feb 2022
- Production: 55.9 in Jan after 50.7 – highest since Feb 2022
- Inventories: 47.6 in Jan after 45.7 – highest since Nov 2025
- Prices paid: 59.0 (cons 59.3, 7 responses) in Jan after 58.5 – highest since Sep 2025
- Employment: 48.1 (cons 46.0, 3 responses) in Jan after 44.9 – highest since Jan 2025
- The marked increase in the overall index follows a particularly strong 11.3pt jump in the MNI Chicago PMI to 54.0 (highest since Nov 2023 although it has recently been a more volatile series than ISM) as well as the average of the five regional Fed manufacturing surveys at the highest since Jan 2025.
- Released shortly beforehand, the final S&P Global US mfg PMI also saw a sizeable upward revision in January to 52.4 (flash 51.9) after 51.8 in Dec for its highest since October.
- In the last 333 months in which there's been a Bloomberg analyst survey, this is the 3rd-largest beat vs the high estimate (Oct 2009 2.6 points, Feb 2007 2.1 points, Dec 2020/Sep 2011/Jan 1999 all 1.7 points...and this was 1.6 points).
- Looking ahead, the new orders less inventories metric had in recent months been pointing to some improvement with a return to positive figures (0.8 av in Q4), but the latest 9.5 in January is particularly impressive at its highest since Aug 2021.
- On the cost side, prices paid nudged a little higher after two months at 58.5 in Nov-Dec and 58.0 in Oct. As such, it doesn’t change the recent narrative and compares with an average of 63.4 in 2025, 53.6 in 2024, a peak of 92 in mid-2021 and a pre-pandemic average in the 49s.
OPTIONS: Expiries for Feb03 NY cut 1000ET (Source DTCC)
Feb-02 15:35
- EUR/USD: $1.1850(E3.5bln), $1.1935-40(E2.5bln)
- USD/JPY: Y155.75($877mln)
- GBP/USD: $1.3200(Gbp835mln)
- USD/CAD: C$1.3590-00($913mln)
SONIA OPTIONS: K6 Call Spread Buyer
Feb-02 15:35
SFIK6 96.60/96.75 call spread, bought for 2 in 10k


