LOOK AHEAD: Eurozone Timeline of Key Events (Times BST)
---------------------------------------------------------------------- Date Time Country Eve...
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
JGBS: Weaker Ahead Of 10Y Supply Tomorrow
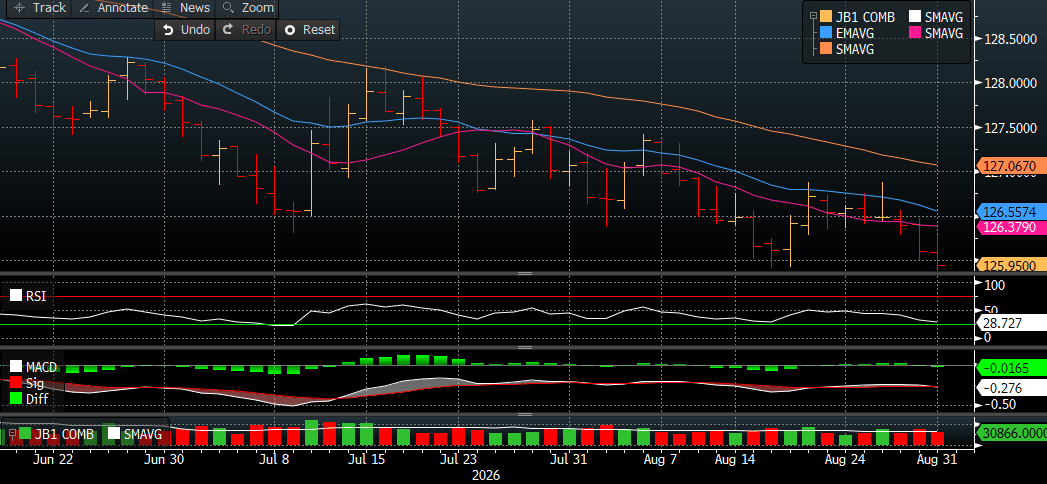
JGB futures are weaker at 125-97 but off session cheaps, -13 compared to settlement levels.
- MNI Techs (JBU6): Resistance in JGB futures remains intact and the trend structure is bearish. A stronger resumption of weakness has put price through support into 126.27, the May 20 low. This break confirms a continuation of the primary downtrend. Key near-term resistance is 128.42, the Jun 15 high. Clearance of this hurdle would instead signal a short-term reversal and highlight a break of the 50-dma - at 127.15.
- (Bloomberg) "US Treasury Secretary Scott Bessent said he expects Bank of Japan Governor Kazuo Ueda "to do the right thing" on monetary policy."
- Cash US tsys are flat to 2bps richer, with a steepening bias, in today's Asia-Pac session after Friday's savage bear-flattener sparked by Fed Chairman Warsh's Jackson Hole economic summit address.
- Cash JGBs are 2-3bps cheaper, with a slight steepening bias.
- (Bloomberg) "Japanese bond yields have climbed sharply, leading analysts to say the Government Pension Investment Fund may be justified in raising its domestic debt allocation target from 25% to seek higher returns."
- Tomorrow, the local calendar will see Q2 Company Sales, Profits & Capex, and S&P Global PMI Mfg alongside 10-year supply.
Bloomberg Finance LP
AUSSIE BONDS: Slightly Cheaper, Infl Gauge Up Ahead Of Wed's Q2 GDP/Price Data
ACGBs (YM -0.5 & XM -0.5) are slightly weaker on a relatively subdued day of trading .
- US tsys are 1-2bps richer, with a steepening bias, in today's Asia-Pac session.
- Given that underlying trimmed mean inflation held at 3.6% y/y in July, the focus will likely remain on data price information.
- The MI inflation gauge for August rose 0.5% m/m bringing the annual rate to 4.8% y/y, highest since December 2023. MI trimmed mean inflation, excluding volatile items, rose to 4.4% y/y from 4.2%.
- Q2 productivity/ULC and price deflators included in Wednesday's GDP release will also be in focus.
- Q2 GDP is forecast to rise 0.3% q/q and slow to 1.9% y/y from 2.5%. Net exports & public demand tomorrow.
- Cash ACGBs are little changed with the AU-US 10-year yield differential at +39bps.
- The bills strip pricing flat to -3 across contracts.
- RBA-dated OIS pricing shows tightening across all meetings, with the probability of a 25bp hike rising from 51% for September to 117% by December 2026.
- The AOFM plans to sell A$300mn of the 4.75% 21 June 2054 bond tomorrow, A$900mn of the 1.25% 21 May 2032 bond on Wednesday and A$800mn of the 4.75% 21 October 2037 bond on Friday.
BUND TECHS: (U6) Fresh Cycle Low
- RES 4: 125.74 High Jul 10
- RES 3: 125.51 High Aug 5 and a key resistance
- RES 2: 124.85 50-day EMA
- RES 1: 124.29 20-day EMA
- PRICE: 123.54 @ 05:53 BST Aug 31
- SUP 1: 123.49 Intraday low
- SUP 2: 123.09 1.000 proj of the Jun 30 - Jul 8 - 10 price swing
- SUP 3: 123.00 Round number support
- SUP 4: 122.46 1.236 proj of the Jun 30 - Jul 8 - 10 price swing
The trend needle in Bund futures futures continues to point south. The contract traded to a fresh cycle low on Friday, reinforcing bearish conditions and maintaining the price sequence of lower lows and lower highs. Note that moving average studies remain in a bear-mode position highlighting a dominant downtrend. Sights are on 123.09 next, a Fibonacci projection. Resistance to watch is around the 50-day EMA - currently at 124.85.


