EQUITIES: EU Cash Opening Calls
Oct-07 06:56
Estox 50: -0.69%, Dax: -0.68%, CAC: -0.77%, FTSE -0.18%, SMI -0.35%....
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
STIR: ECB-dated OIS Price 75bps of Hikes Through Mid-27; ECB Decision Thurs
Sep-07 06:51
ECB-dated OIS continue to price around three 25bp hikes through the middle of next year, including a fully expected hike on Thursday.
- Implied hikes are up to 2bps more hawkish than Friday’s close, owing to fresh upside in energy benchmarks (even as both oil and gas are off session highs at typing). There are heightened concerns for prolonged Middle East supply disruption after US strikes on Iranian tankers and Iran’s threat of a new restricted zone outside the Strait of Hormuz.
- The ECB is unanimously expected to hike the deposit rate to 2.50% on Thursday. A September move has been the baseline expectation for some time now, with the ECB’s reaction function guidance suggesting a “measured adjustment” of policy is the appropriate response to the US-Iran war energy shock. Continued upside in energy benchmarks and a more resilient than expected economy have cemented these expectations, even as spot inflation readings have come in below the June baseline projections and second round inflation effect risks continue to appear contained.
- Focus will be on the updated macroeconomic projections and press conference guidance, specifically whether the communique is supportive - or at least, not inconsistent with – market pricing. A hike to 2.50% in September would bring the deposit rate to the top of Chief Economist Lane’s new nominal neutral rate upper bound, and some hawkish Governing Council members have already opened the door to further moves.
| Meeting Date | ESTR ECB-Dated OIS (%) | Difference Vs. Current Effective ESTR Rate (bp) |
| Sep-26 | 2.443 | 25.4 |
| Oct-26 | 2.504 | 31.5 |
| Dec-26 | 2.658 | 46.9 |
| Feb-27 | 2.726 | 53.7 |
| Mar-27 | 2.832 | 64.3 |
| Apr-27 | 2.870 | 68.1 |
| Jun-27 | 2.923 | 73.4 |
| Jul-27 | 2.939 | 75.0 |
| Sep-27 | 2.957 | 76.8 |
| Source: MNI/Bloomberg Finance L.P. | ||
STIR: Just Over 30bp Of BoE Hikes Priced Through Year-End
Sep-07 06:46
GBP STIRs see hawkish adjustments alongside upside in energy prices, driven by the latest rounds of fire on ships in and around the Strait of Hormuz.
- BoE-dated OIS moves to price ~31bp of hikes through year-end vs. ~30bp late on Friday.
- SONIA futures flat to -4.0. SFIM7 is still 14.5 above last week’s lows, with energy price swings and wider cross market moves dominating.
- Expect cues from energy markets to continue to dominate for much of today’s session.
- Overnight, the KPMG-REC Report on Jobs continued to point to a labour market that is soft, albeit with the rate of decline slowing. There isn't a clear conclusion (any different to the July release) for the MPC to draw from the release, in our opinion.
- In terms of scheduled event risk, Chancellor Healey will speak around 09:30 London. Reports have noted that he will focus on broadening regional growth across the UK, while vowing fiscal discipline. Market participants will be eying the speech for any clues surrounding the October Budget. However, such information may not be forthcoming at this stage.
BoE Meeting | SONIA BoE-Dated OIS (%) | Difference vs. Current Effective SONIA (bp) |
Sep-26 | 3.763 | +3.3 |
Nov-26 | 3.900 | +17.0 |
Dec-26 | 4.042 | +31.2 |
Feb-27 | 4.177 | +44.7 |
Mar-27 | 4.281 | +55.1 |
Apr-27 | 4.363 | +63.2 |
Jun-27 | 4.416 | +68.5 |
GERMANY: AfD Fails To Secure Majority In Saxony-Anhalt; Coalitions Likely Tricky
Sep-07 06:38
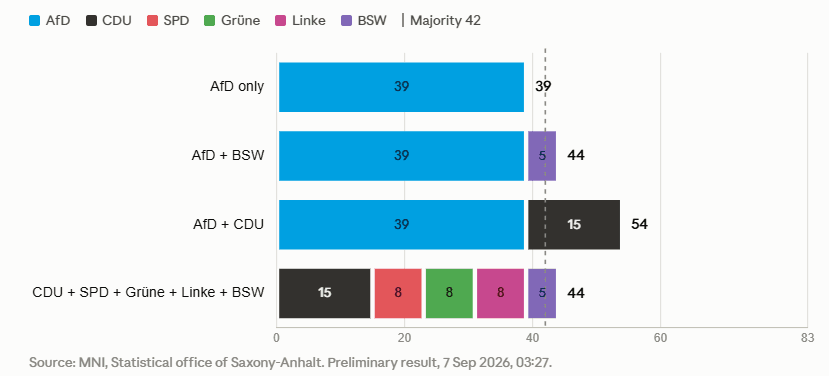
- German AfD (right-wing) fails to secure an absolute majority of seats in Saxony-Anhalt state elections on Sunday, however, winning clearly, with 43.8% of votes (+23.0pp vs 2021). Elsewhere, CDU (centre-right) lost out massively, winning 17% of votes (-19.9pp), while SPD (centre-left), Greens (centre-left) and the Left (left-wing) as well as BSW (left-wing) also cleared the 5% thresholds needed for seats in parliament. With prediction markets having priced this scenario at above 75% going into the vote, the outcome does not come as a surprise.
- CDU continues to exclude cooperation with the AfD, hence coalition building will likely prove difficult. A coalition of CDU, SPD, Greens, Linke and BSW would have enough seats but would be seen as a big compromise by all parties involved as per the different nature of their views on a range of topics. BSW could be considered 'Kingmaker' now as they have not excluded explicitly working with AfD but are reportedly looking for a non-partisan candidate as Minister President.
- The potentially highest risk scenario from a federal perspective would be that local CDU representatives start calling for an end of the 'firewall' against AfD and look for cooperation with the right-wing party. Such an outcome could pose a fundamental challenge for federal CDU (which continues to remain firm on the blocking of any cooperation with AfD, the 'firewall'), meaning Chancellor Merz will try to circumvent this at very high costs.
- Next German state-level elections will be on September 20, in Mecklenburg-Pomerania and Berlin. For polling charts in these states, see page 4 of our analysis published last Thursday.