CHINA DATA: CPI Pressures Remain Benign, PPI Aided By Higher Commodities, Base Effects
China May inflation data was close to expectations. Headline CPI rose 0.3% y/y, against a 0.4% forecast and 0.3% in April. The PPI was -1.4% y/y, against a -1.5% forecast and -2.5% prior.
- The detail on the CPI still suggests quite a benign domestic price backdrop. In m/m terms prices fell 0.1%. Consumer good prices were flat in y/y terms, services were 0.8% y/y, unchanged from April. Goods price deflation has ended, but services prices are off the pace from the second half of 2023.
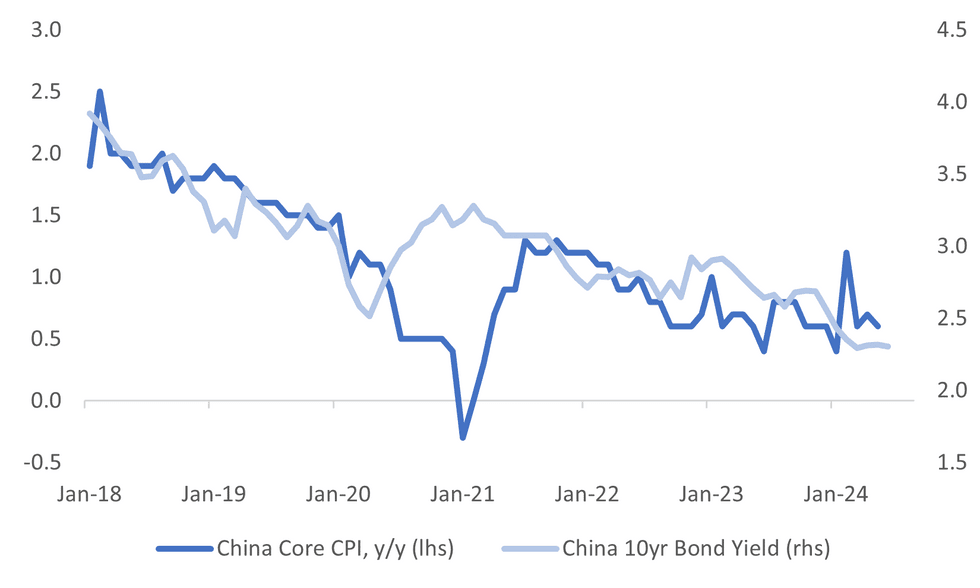
- Core inflation (ex food and energy) was 0.6% y/y, down slightly from April's 0.7% pace. The trend remains benign, albeit up from recent lows. The chart below overlays the 10yr CGB yield against core CPI y/y.
- In terms of the sub categories, we saw drags from food and transport. The main positives were clothing, recreation and the other segment. Only one category saw a pick up in y/y pace versus the April outcome, which was food, but it remained negative in an outright sense.
Fig 1: China Core CPI Y/Y Versus 10yr CGB Yield
Source: MNI - Market News/Bloomberg
- For the PPI, base effects are favorable for a further improvement in y/y momentum over the next few months.
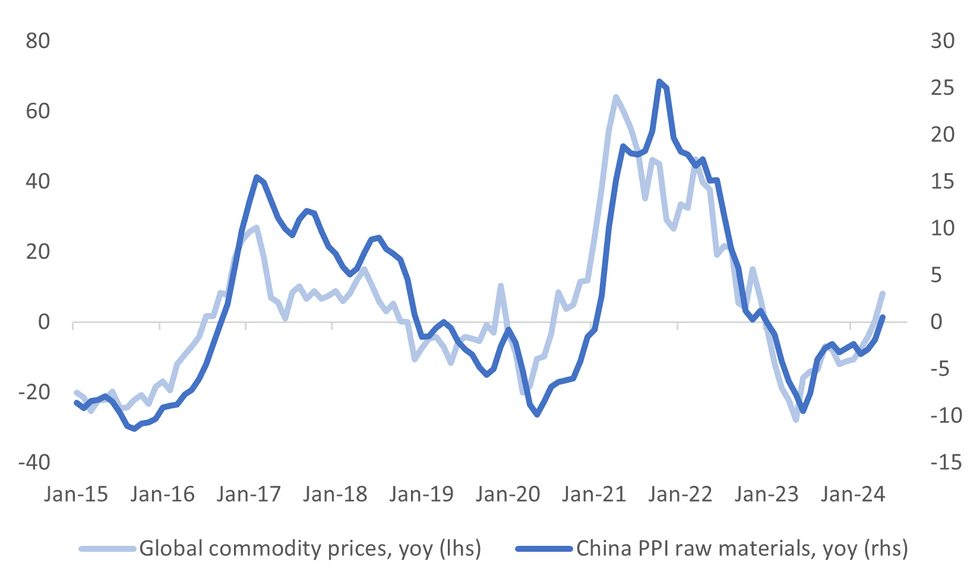
- The global commodity price backdrop is also helping. The second chart below plots the raw materials sub index of the PPI (which ticked up into positive territory, +0.5% y/y), against spot global spot commodity price changes y/y. Mining and manufacturing PPI's were also less negative in y/y terms in May.
- Consumer goods remained negative and close to the April y/y pace.
Fig 2: China PPI Raw Materials & Global Commodity Prices Y/Y
Source: MNI - Market News/Bloomberg
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
FOREX: Risk Off Evident In G10 Currencies, USD/JPY Dips Supported Despite Higher Yields
G10 forex trends have reflected a more risk off tone in recent dealings. The BBDXY is a touch higher, last near 1254.4, with AUD and NZD underperforming against the majors.
- USD/JPY gapped lower to 155.50/55 as the BoJ curbed its bond buying ops for the 5-10 year tenor compared to the late April operation. JGB yields are pressing higher, with the 10yr at multi month highs near 0.94%.
- Still, USD/JPY dips have been supported, the pair is back to 155.85 in latest dealings. We haven't been able to test 156.00 yet though.
- AUD/USD is down 0.25% to sub 0.6590. The weaker tone to China equities, followed weaker credit data from the weekend and looming US tariff increases is a factor. Equity trends are mostly negative elsewhere as well.
- On the data front, the NAB business conditions print for April was close to unchanged (+7, versus +9 prior0. Confidence was steady at +1.
- NZD/USD has also weakened, down 0.20% to 0.6010.
- We still have NZ inflation expectations due in around an hour.
CHINA PRESS: Sino-German Relationship Lowers EU Trade Tensions
The EU will be less likely to take protectionist measures against China given Germany’s strong economic relationship with Beijing, according to Zhu Ying, professor of economics at Shanghai Normal University. Germany plays a special role in China's economy and trade relations, with about 5,000 firms operating in the country, Zhu added. Automakers from Germany are increasingly relying on Chinese teams for R&D in areas such as autonomous driving, where Europe is not advanced. (Source: Yicai)
CHINA PRESS: April M2 Slows On Decreasing Bank Deposits
The deceleration of M2 money supply growth was mainly driven by residents' increasing enthusiasm for buying financial management products which have diverted bank deposits, and also reduced the need for non-bank institutions to borrow from banks, Yicai.com reported citing Zhang Yu, chief macro analyst at Huachuang Securities. More than CNY2 trillion of companies’ and residents’ deposits were diverted to asset-management products in April from March, an unnamed source said. Meanwhile, a considerable number of inflated and irregular deposits and loans have been reduced amid tightening regulations, which also slowed down M2 growth to 7.2% y/y in April from March’s 8.3%, Zhang noted.


