US: "*COREWEAVE EYES AT LEAST $4B FROM INVESTMENT-GRADE LOAN SALE" - BBG
"*COREWEAVE EYES AT LEAST $4B FROM INVESTMENT-GRADE LOAN SALE" - BBG...
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
AUSSIE BONDS: Little Changed As Markets Take A Breather With US Mkts Closed
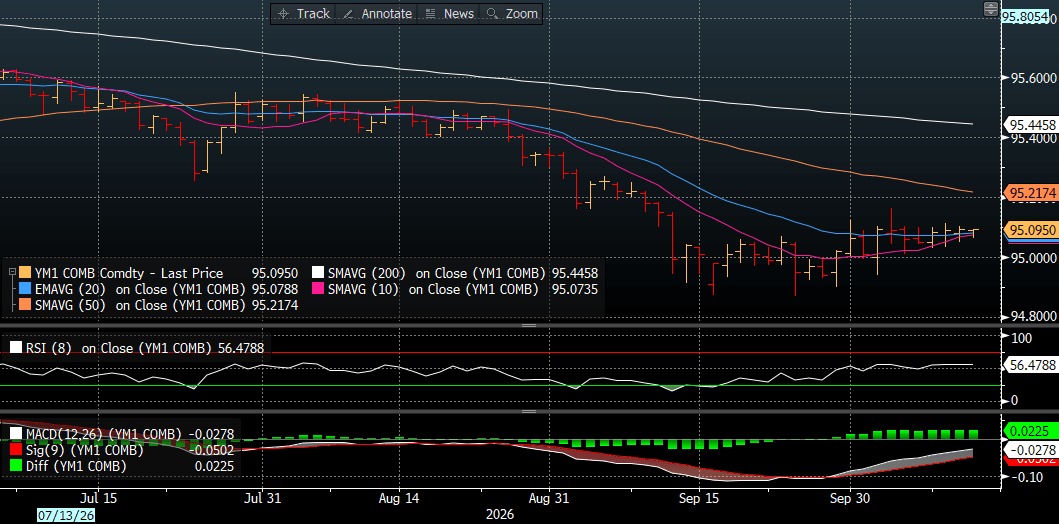
ACGBs (YM flat & XM -0.5) are little changed with cash US tsys closed yesterday for the Columbus Day holiday.
- Ahead of September's RBA decision, we noted that a dovish hike could potentially trigger a material rally in the short end if it prompted the market to substantially unwind its then-priced expectation of three further 25bp hikes.
- The 3-year contract is currently around 13bps richer than pre-RBA levels with hike expectations pared by around 2/3 of a 25bp hike.
- However, it is worth reiterating that the 3-year yield has typically peaked around the time of the RBA's final hike.
- The bills strip pricing is little changed across contracts.
- RBA-dated OIS pricing shows tightening across all meetings, with the probability of a 25bp hike rising from 33% for November to 84% by February 2027 and 112% by June 2027.
- Today, the local calendar will see RBA Minutes of Sept. Policy Meeting and NAB Business Confidence.
- This week, ACGB supply will be in line with the recent average weekly issuance of $2000mn. The AOFM plans to sell A$300mn of the 3.00% 21 March 2047 bond today, A$700mn of the 4.25% 21 March 2036 bond on Wednesday and A$1000mn of the 3.25% 21 April 2029 bond on Friday.
Bloomberg Finance LP
BONDS: NZGBS: Little Changed, US Was Closed For Columbus Day
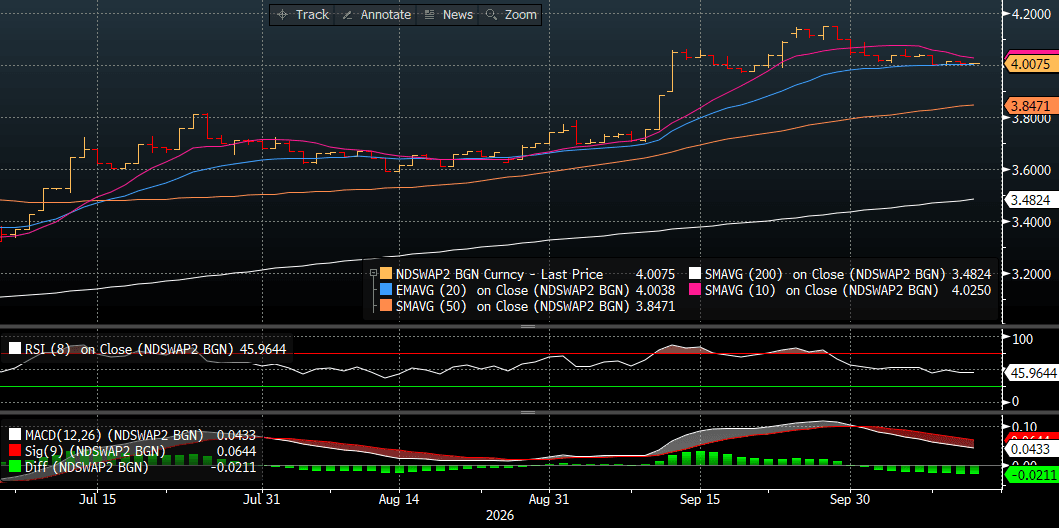
NZGBs are 1bp cheaper with cash US tsys closed yesterday for the Columbus Day holiday.
- September food and other monthly price indicators, including rents, petrol and electricity, are due on Friday and should help shape Q3 CPI expectations. Food prices trended lower in July and August, while rental increases were close to zero.
- The data could also influence swap-rate direction, particularly at the 2-year tenor, given the potential implications for OCR terminal-rate expectations.
- Swap rates are unchanged today, with the 2-year at 4.01%. With the expected OCR peak currently around 3.80%, and 2-year swap rates historically peaking around 50bps above the eventual OCR peak during previous tightening cycles, this framework points to a potential 2-year target of around 4.30%.
- With the 2-year trading near the bottom of its 3.95–4.15% range, which has held over the past month, paying ahead of Friday’s price indicators could offer an attractive potential risk/reward opportunity.
- RBNZ-dated OIS pricing is little changed across meetings. 16bps of tightening is priced for October, while February 2027 and August 2027 assign 52bps and 105 bps, respectively.
- On Thursday, the NZ Treasury plans to sell NZ$225mn of the 2.00% May-32 bond, NZ$175mn of the 4.25% May-36 bond and NZ$50mn of the 5.00% May-54 bond.
Bloomberg Finance LP
CNH: Outperformance Continues, EUR/CNH Consolidates Break Sub 7.5000
Spot USD/CNH couldn't test sub 6.6900 as Monday trade unfolded, the pair tracks near 6.6950 in early Tuesday dealings. CNH lost a little ground versus the USD as Monday trade unfolded, as broader USD indices rose (BBDXY up a little over 0.10%, DXY +0.36% firmer). Higher energy prices amid Ukraine's Zelekskyy saying Russia has violated the "energy ceasefire" between the two nations as well as continued firm rhetoric from Iran prompted a renewed advance for USD indices (the DXY through recent highs above 102.5). The CNH outperformance theme remained firmly intact though. Spot USD/CNY finished up at 6.6938, while the CNY CFETS basket tracker edged a little higher to 103.585.
- For spot USD/CNH, broader downtrend conditions are still maintained for the pair. Downside focus will remain on a sub 6.6900 test, while we remain under all key EMAs, with the 20-day at 6.7050 currently.
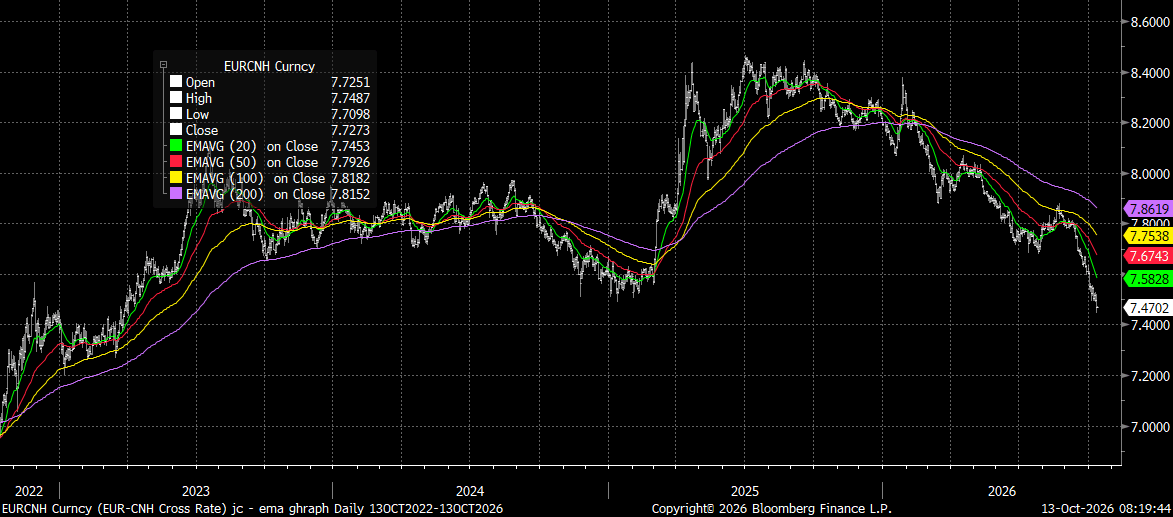
- EUR/CNH tested fresh cycle lows on Monday, getting to 7.4470 (last 7.4700), as the pair looks to consolidate its break under 7.5000. Mid March 2023 lows were just under 7.2700 for the pair (see the long run chart below). CNH/JPY is currently at 23.6920 fresh highs since early Sep. Highs just short of 23.85 from that period will be an upside focus point.
- CNH remains immune to higher US-CH yield differentials, continuing to present as somewhat of a safe haven to higher UST yields and the negative terms of trade shock. Focus will remain on push back from the authorities around yuan outperformance, with first signs likely to appear in the CNY fixing outcome.
- On the data front, we still await Sep new loans/aggregate finance figures, while tomorrow delivers Sep inflation and trade balance figures.
Fig 1: Spot EUR/CNH
Source: Bloomberg Finance L.P./MNI


