US DATA: Core Retail Sales Still Strong, But Slowdown Still Implied For Q4
Jan-14 13:51
November retail sales were solid on all counts, though October's very strong report was revised down to slightly less robust (but still quite strong) levels. Overall there is no sign of a retail consumption slowdown toward the end of 2025, though this report may marginally downgrade tracking estimates for Q4 private consumption (depending on one's assumptions for core sales in Nov).
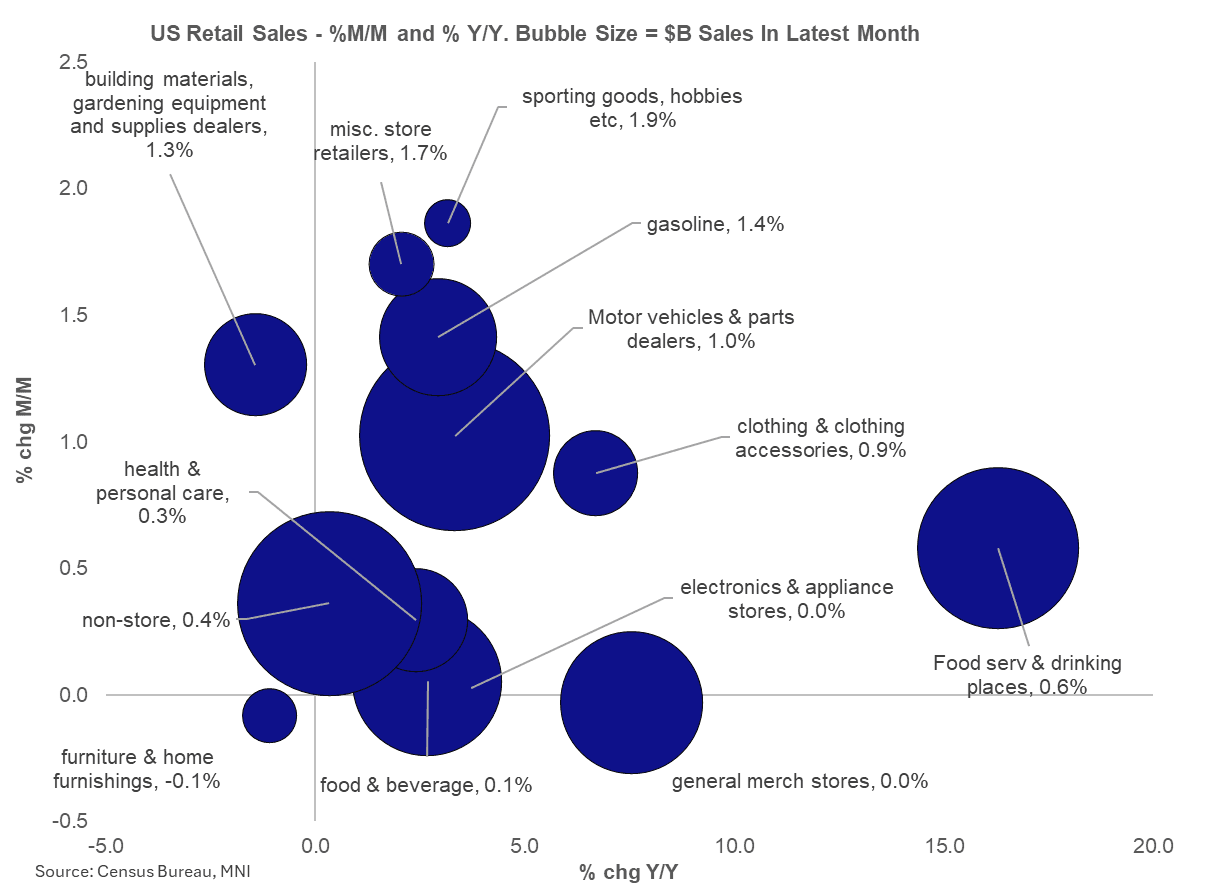
- Headline sales beat expectations rising 0.6% (prior was rev down to -0.1% from 0.0%), but this was largely - as expected - due to strong motor vehicles/parts (+1.0% after -1.6%) and gasoline (+1.4% after -1.2%) sales, neither of which feed into the key GDP-input Control Group metric.
- The latter rose by 0.4% M/M, right in line with consensus but the October reading of 0.85% M/M was revised down fairly substantially to 0.61%. Ex-autos accelerated to 0.5% (0.2% prior; and above Chicago Fed CARTS' 0.3% expected) with ex-autos/gas steady at 0.4%.
- The major reason for the October downgrade to Control Group sales was non-store (ie online) retail which originally posted growth of 1.8% that has now been revised down to 1.0%. It then followed this up with 0.4% M/M in November.
- Indeed it was largely categories outside of the Control Group that had the most impressive gains: this included not just the aforementioned autos and gas, but also building materials (+1.3% after -1.3%), and key to services, food/drinking establishment sales rose to 0.6% after -0.1% (this was revised up from -0.4%).
- From a GDP tracking perspective, this report may result in a softer expectation for personal consumption in Q4 than previously expected, given that October's very strong Control Group figure was key to a strong base effect for the quarter.
- The Atlanta Fed's GDPNow metric estimates real PCE growth of 3.0% Q/Q SAAR in Q4 after 3.5% in Q3. It's unclear whether this report warrants a slight downgrade (it depends what they assumed for November) but either way a gradual slowdown estimate vs Q3 appears justified by recent tracking of retail Control Group growth.
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
GLOBAL POLITICAL RISK: Week Ahead 15-21 December
Dec-15 2025 13:41
Download Full Report Here
(MNI) London – All timings are subject to change.
Monday 15 December
- Ukraine: German Chancellor Friedrich Merz holds a bilateral meeting with Ukrainian President Volodymyr Zelenskyy in Berlin to discuss economic links and the status of the war. In the evening, European heads of government and state, and EU and NATO leaders, will join for a broader conversation regarding the nascent peace plan framework, as well as the 5+ hours of talks between Ukrainian and US delegations over the weekend that are due to continue into the morning. The German government has confirmed the US delegation is invited to attend, but at the time of writing it is unclear if this will be taken up.
US TSYS: Post-Empire Mfg React
Dec-15 2025 13:38
- Treasuries bounce back near late overnight highs after Empire Mfg data came out lower than expected - Mar'26 10Y contract trades 112-13 to -13.5 (+7.5-8), 10Y yield -.0234 at 4.1606%.
- A bearish theme in Treasuries remains intact and short-term gains appear corrective. The rally last Thursday topped out at 112-23, meaning resistance at the 20-day EMA, currently at 112-21, remains intact. A continuation lower would refocus attention on key short-term support at 111-29, the Dec 10 low.
- Clearance of this level would confirm a resumption of the bear leg and signal scope for an extension towards 111-19, a Fibonacci projection.
CANADIAN NOV CPI UNCHANGED AT 2.2% YOY VS FORECAST 2.3%
Dec-15 2025 13:30
- CANADIAN NOV CPI UNCHANGED AT 2.2% YOY VS FORECAST 2.3%
- CANADA NOV TRIM AND MEDIAN CORE CPI BOTH SLOW TO 2.8% FROM 3%
- CANADA NOV CPI EX FOOD & ENERGY -0.4% MOM; 2.4% YOY


