CHINA: "*CHINA'S CXMT TO BEGIN HBM3E CHIP PRODUCTION IN 2 MONTHS: RTRS" - BBG
"*CHINA'S CXMT TO BEGIN HBM3E CHIP PRODUCTION IN 2 MONTHS: RTRS" - BBG...
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
ASIA STOCKS: China Markets Slump Amid Multiple Headwinds, SK Returns Weaker
China markets are weaker to start the week, the CSI 300 off over 2%, the index falling to fresh lows back to Sep 2025. Returning South Korean markets are down over 2%. Indian markets are also weaker, but moves elsewhere aren't large. US equity futures are weaker, led by the tech side. Eminis last off around 0.35%, while Nasdaq futures are off 0.70%. Higher oil, with Brent up 2.5%, and rebounding UST yields (as the Hormuz impasse continues between US-Iran) is impacting sentiment and spilling over to US equity futures.
- The CSI 300 was last putting the index back around 4345, which is fresh lows back to early Sep 2025. The Chinext index is down over 4%, leaving this index back near early April 2026 lows. Earlier data showed China industrial profits up 4.2%y/y for Aug, versus a 11.2% gain prior. This is the softest rise since Nov's -13.1% print last year. In YTD terms, we were 15.7%, versus 17.6% in July. The data continues to highlight the challenging economic backdrop for China. Also note: "Chinese chip stocks drop after a report that China may allow purchases of Nvidia’s new chips, with broader tech sentiment was also hit by a selloff in optical stocks following a proposed US transceiver bill." - BBG
- South Korean markets have returned, after being out for the final two days of last week. The Kospi is back under 7000, off 2.15% currently. Tech stocks were mostly higher in Friday trade, but sit off recent highs in terms of the SOX/MSCI IT indices. Via BBG as well: For SK Hynix, media reports of a potential listing of its US subsidiary added to worries over the firm’s complex ownership structure."
- Indian markets are down over 1% for the Sensex and NIFTY. The higher oil backdrop a likely headwind in the first part of trade today.
- In South East Asia, most markets are lower. Indonesia is down around 1%.
JGBS: Still Eyeing 124.00 Downside Test, Cash JGB Yields Up, Front End Leads
JGB futures sit at 124.20, -.15 versus settlement levels in latest dealings. Earlier cycle lows were at 124.05, with 124.00 a downside target, followed by 123.6 (a technical target). We are oversold per RSI (14), but firm downtrend risks persist. Sep 18 highs were 125.49 in terms of upside resistance. The regional/UST futures skew is lower on the back of higher oil futures amid the on-going US-Iran impasse over Hormuz. Cash UST yields are rebounding (+2-5bps led by the front end).
- Cash JGB yields are higher, but led by the front end as well. The 2y is closing in on a 2% upside test, last near 1.98% (up close to 4.5bps so far today). 10-40yr tenors are up around 2bps at this stage, leaving curves with a modest flattening bias. The 2/30s were last +113bps, against recent highs of +117bps.
- We had the BoJ minutes out from the July policy meeting out earlier. These are quite dated now, but show a clear bias to tighten further, amidst still easy financial conditions and rising confidence in the achieving the 2% inflation target. Uncertainty remained though around the pace of tightening.
- The PPI services print for Aug rose 3.7%y/y, slightly above the 3.6% forecast. This takes the y/y rise back to 2024 highs. On Thursday, the Q3 Tankan is out, then on Friday the Tokyo CPI for Sep.
- On the supply front, tomorrow's 40yr debt sale will be the main focus point this week.
GOLD: Momentum Turning Lower, Potentially Targeting The Bottom Of Range
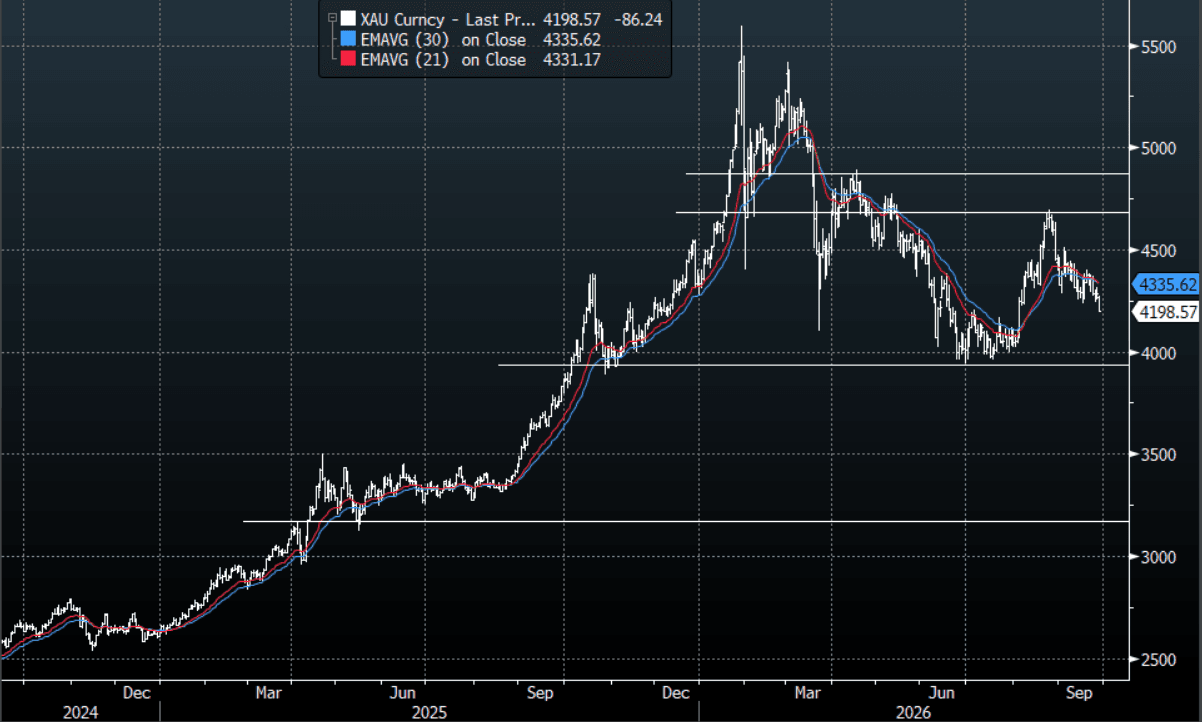
The range for Gold today in the Asia-Pac has been $4,191.57/oz - $4,275.23/oz, Asia is currently trading around $4197, -2.05%. The precious metal is picking up some momentum moving back toward the lows within its wider range. For the moment the competing forces for Gold could see it continue to chop around within the wider $3900-4900/oz range while the market works out how long this US hiking cycle could be as the Fed fights inflation and what that means for the US Dollar which is now attempting to break higher. Central banks though continue to acquire gold, China chief among them. Without all this institutional demand how much lower would Gold be ?
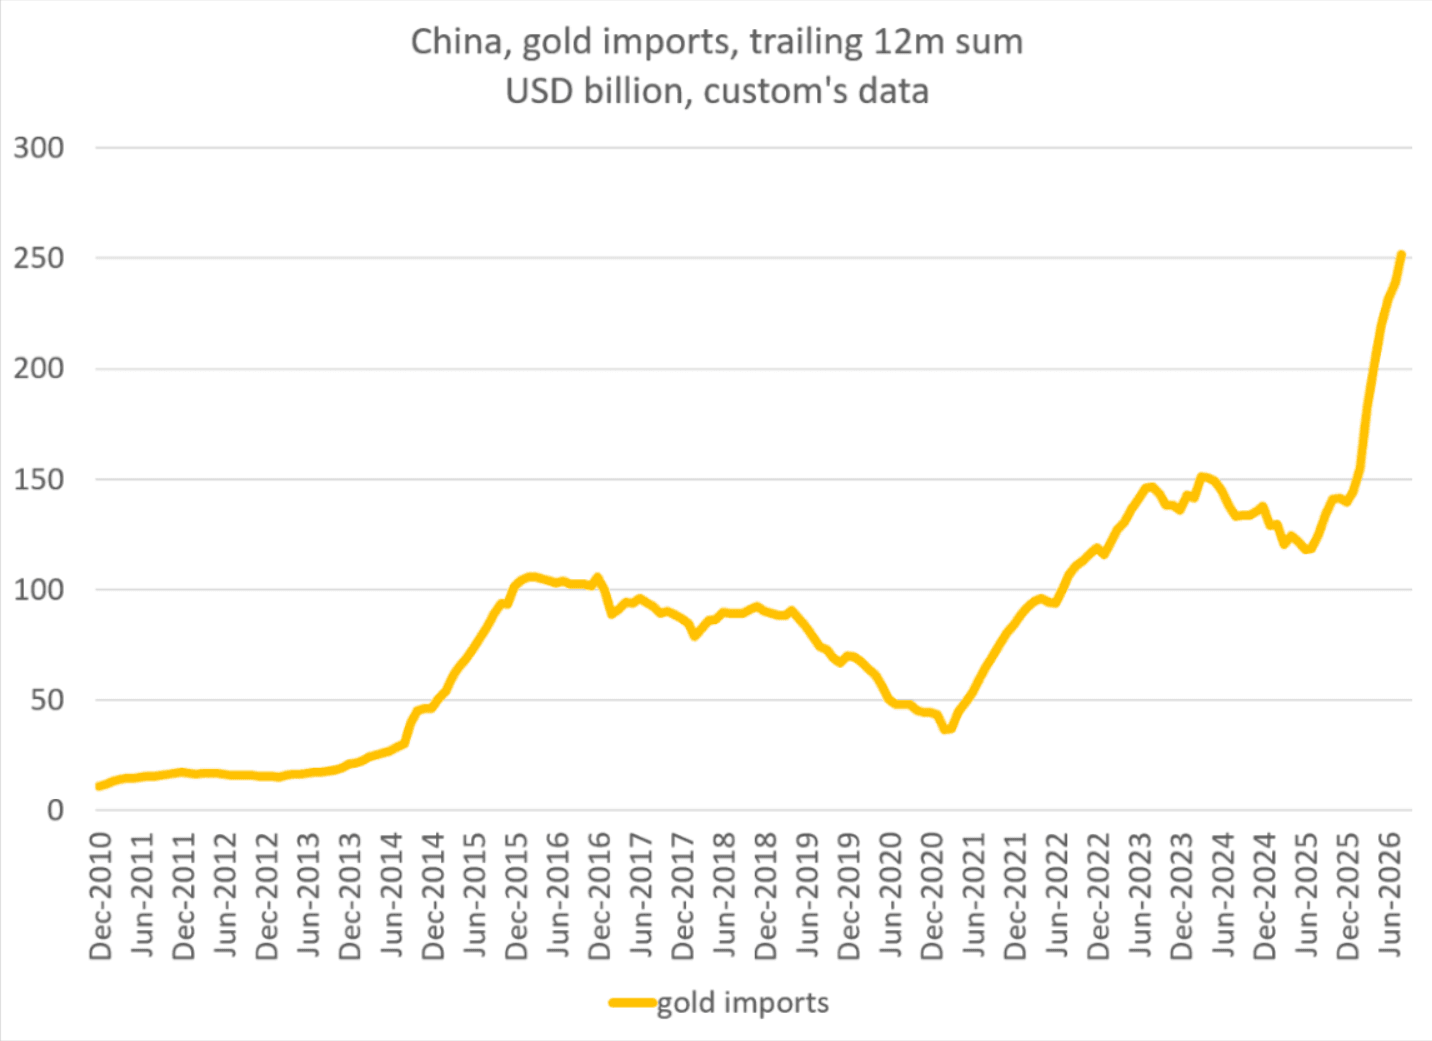
- Brad Setser: “A chart of Chinese gold imports (on a trailing 12m basis) looks a bit like a chart of Korean chip exports (or US computer imports). Curious how the IMF and others will handle this. The surge in imports of gold is really a surge in imports of financial assets -- yet it registers in the customs data and is big enough to have a material impact on the goods balance/ net exports.” Fig.1 below.
- (Financial Times) via BBG -- “China has spent a record sum importing more than 1,000 tonnes of gold this year as the central bank and local investors pour cash into bullion amid rising geopolitical tensions abroad and poor returns…”
- The XAU Average True Range(ATR) for the last 10 Trading days: $72.00/oz
Fig 1 : China Gold Imports
Source: MNI - Market News/@Brad_Setser
Fig 2 : Gold Daily Chart
Source: MNI - Market News/Bloomberg


