US DATA: Broadly Steady Unemployment Rates At Healthy Levels [1/2]
Sep-04 15:33
The unemployment rate increased slightly in August with an even smaller rise in the prime age rate, ...
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
FED: US TSY 17W BILL AUCTION: HIGH 3.785%(ALLOT 94.66%)
Aug-05 15:32
- US TSY 17W BILL AUCTION: HIGH 3.785%(ALLOT 94.66%)
- US TSY 17W BILL AUCTION: DEALERS TAKE 29.27% OF COMPETITIVES
- US TSY 17W BILL AUCTION: DIRECTS TAKE 6.18% OF COMPETITIVES
- US TSY 17W BILL AUCTION: INDIRECTS TAKE 64.56% OF COMPETITIVES
- US TSY 17W BILL AUCTION: BID/CVR 3.19
US TSYS/SUPPLY: Buybacks Maintained For Upcoming Quarter
Aug-05 15:31
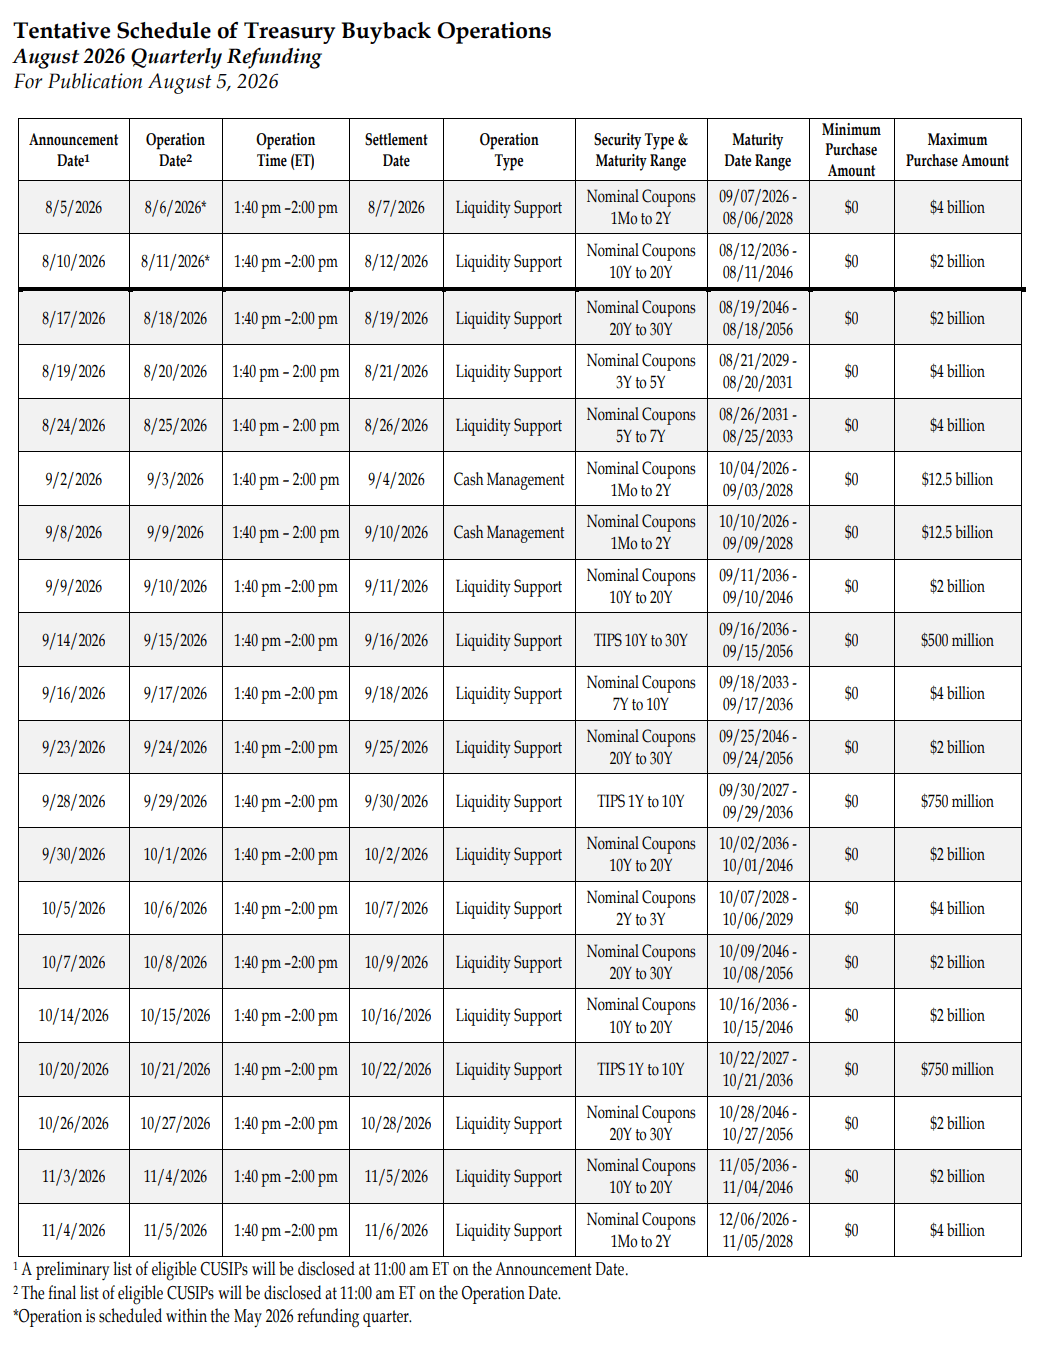
Treasury's buyback program for the upcoming quarter is unchanged, as expected (though if anything we had seen some speculation that sizes could be increased).
- Treasury will again buy up to $38B in off-the-run securities for liquidity support, and up to $25B in 1-month to 2-year securities for cash management purchases (the latter across 2 operations in mid-September).
- Schedule is below.
US TSYS/SUPPLY: Implied Bill Funding Over Rest Of 2026 Around 50% Of Total (2/2)
Aug-05 15:25
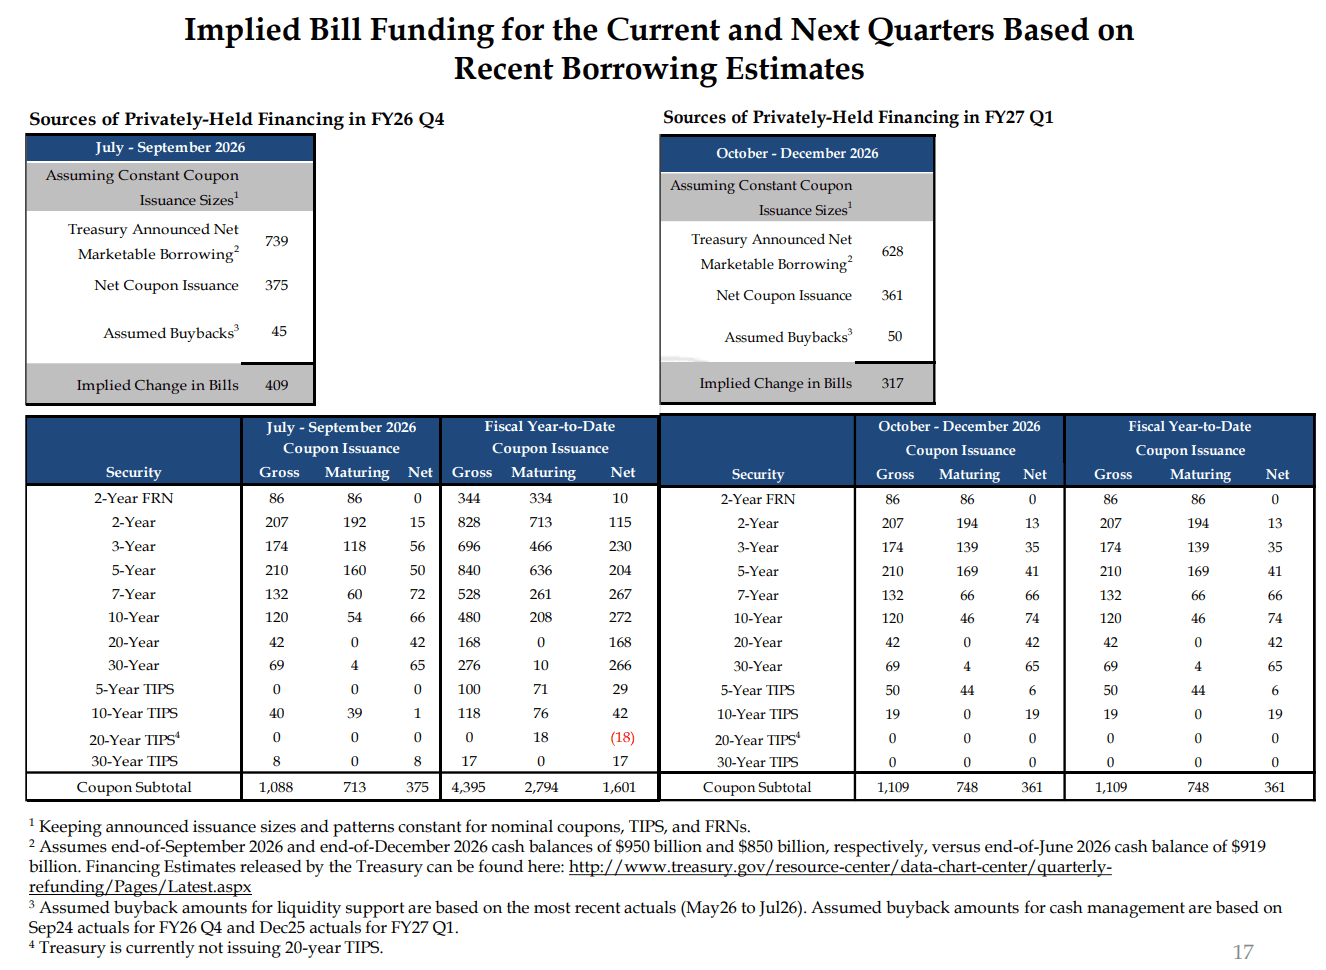
Below is Treasury's table of implied privately-held bill vs coupon funding over the current and next quarters assuming no changes in nominal coupons/TIPS/FRNs vs previous. Net coupon issuance for the current quarter (Jul-Sep) is implied at $375B with bills $409B; for next quarter (Oct-Dec) those figures are $361B and $317B, respectively.
- The implication is that bills will still be around 50% of net issuance through year-end. (In the Apr-Jun quarter, net bill issuance was negative, as is typical around the key mid-April tax intake). Most analyst expectations are lower than the above figures however, and the impact of continued Fed reserve management purchases/MBS rollover means around $75B of bills taken off the market per quarter. (Net marketable borrowing figures in the table below are implied bill change + net coupon issuance minus buybacks).
- What We Didn't Hear About: A few topics of interest - some of which Treasury had asked primary dealers about beforehand - didn't see any action in this Refunding.
- There was no decision on changing the structure of 7Y auctions which could move to a schedule that includes new quarterly issuance with reopenings. The TBAC minutes note "Most dealers expressed little to no balance sheet concerns about the possibility of scheduling the quarterly new issue auction just ahead of the end of each calendar quarter. TBAC members had no additional feedback"
- Additionally there was no action on Treasury investing excess cash from the TGA into the repo market. From the TBAC minutes: "A plurality of primary dealers prefers a stable repo investment allocation, but views are mixed overall. Some respondents argued that a consistent investable repo balance might command a premium and that counterparties would be less likely to bid aggressively for Treasury’s investable cash if much of that liquidity were withdrawn periodically. Although day-to-day variability of $25-50 billion is generally perceived to be manageable, respondents uniformly suggested that advance guidance around Treasury’s planned repo activity would be instrumental to the potential program’s success. Most primary dealers are optimistic that such a program, if designed well, would at least modestly ease funding constraints, increase intermediation capacity, and thereby improve the market’s ability to absorb additional Treasury securities."
- Elsewhere, TBAC provided Treasury with its thinking on other topics: additional transparency of secondary market transactions; and the development of intraday repo.