EM CEEMEA CREDIT: Banque Ouest Africaine de Developpment: FV € 15Y
(BOAD; Baa1/NR/BBB)
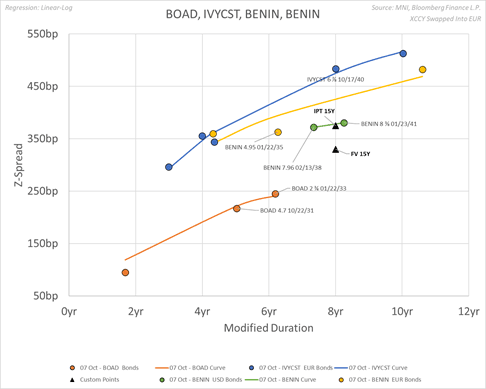
IPT 15Y MS+375bp area
FV MS+330bp
- We sketch our FV considerations looking at the seasoned BOAD bonds, both € and $ x-ccy swapped into €. In particular, we see some 85bp spread pick up vs the BOAD € 33s charting at z+245bp area.
- For additional comparables, we focus on sovereign issuers and other development agencies in the region. We look at lower rated Cote D’Ivoire (IVYCST; Ba2/BB/BB-) and Benin (BENIN; B1pos/BB-pos/B+). IVYCST € Oct40 chart at z+485bp whilst BENIN $ Jan41 chart at z+377bp on x-ccy in EURs (see chart below).
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
LOOK AHEAD: US Macro: PPI (Wed) and CPI (Thu) Inflation
US PPI inflation is released on Wednesday before CPI inflation on Thursday, an unusual ordering that should see core PCE implications dialled in after the CPI release rather than the usual wide range waiting for specific PPI details. PPI will be watched more closely than usual this month after a far stronger than expected jump in last month’s July report fired a warning short over tariff-based cost pressures starting to feed through. That included a 0.6% M/M increase in our preferred core series of PPI ex food, energy & trade services, which strips out items such as the then booming portfolio management & investment advice category following the strength in equity markets. It's too early to gauge an accurate sense of analyst expectations for August.
CPI inflation on Thursday will then be the last major release ahead of the Sep 17 FOMC decision. Consensus looks for core CPI at 0.3% M/M after the 0.32% M/M in July, another monthly increase comfortably above a pace consistent with 2% inflation. August should in theory start to see the largest tariff impacts along with September and possibly October. Returning to July’s report, core goods inflation was softer than expected, at a still solid (by core goods standards) 0.2% M/M for a second month running but about half that of 0.4% expected by analysts. Instead, non-housing core services surprised higher. The latter was a “dangerous” development in the words of a usually dovish Chicago Fed’s Goolsbee (’25 voter), who speaking after Friday’s payrolls report is still undecided on a September cut whilst looking for August inflation data “to get more information”.
LOOK AHEAD: US Macro: Payrolls Preliminary Benchmark Revisions (Tue)
- The BLS on Tuesday will publish preliminary estimates of benchmark revisions, based off QCEW data for Q1.
- These will give an indication of the actual benchmark revisions on the Mar 2025 level of payrolls due with the Jan 2026 payrolls report released in early February.
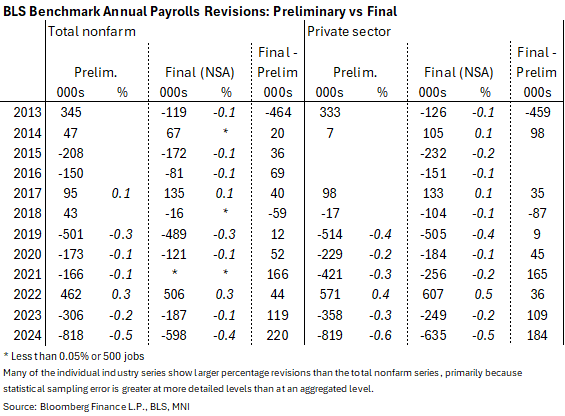
- Bear in mind that the final benchmark estimate tends to nearly always be more negative than the preliminary figure – see historical values to the right.
- That doesn’t mean they can’t be large again after last year’s historically negative revision that lowered the level of payrolls by ~600k. Initial estimates we’ve seen look for another large downward revision, with the smallest being worth -550k but with wide ranges higher.
FED: Barclays Adds A Cut To 2025 Fed View
Barclays analysts now expect three Fed cuts in the remainder of the year, adding October to their pre-existing call for 25bp reductions in September and December. "Given the disappointing August employment report, we expect the FOMC to see more elevated downside risks to the employment side of the mandate."
- As for a 50bp September cut, "we think that the FOMC will view [that] as sending too strong a signal that labor market conditions are deteriorating. Indeed, we think that participants such as Powell understand that the slower pace of payroll employment reflects at least, in part, slower labor supply, which does not translate into increased labor market slack."
- For 2026 they continue to expect 25bp cuts in March and June to 3.00-3.25%, but "we do not think the FOMC will be able to cut rates more than twice next year, as we think that activity will show some slight acceleration, with the economy adapting to the new tariff environment and fiscal policy providing some support, and the unemployment rate will revert down amid limited increase in labor supply."


