US TSYS: Asia Wrap - Yields Have Little Reaction To Cook News For Now
The TYZ5 range has been 113-06 to 113-09+ during the Asia-Pacific session. It last changed hands at 113-08+, down 0-02 from the previous close.
- The US 2-year yield has edged higher trading around 3.493%, up 0.01 from its close.
- The US 10-year yield has edged lower trading around 4.045%, up 0.01 from its close.
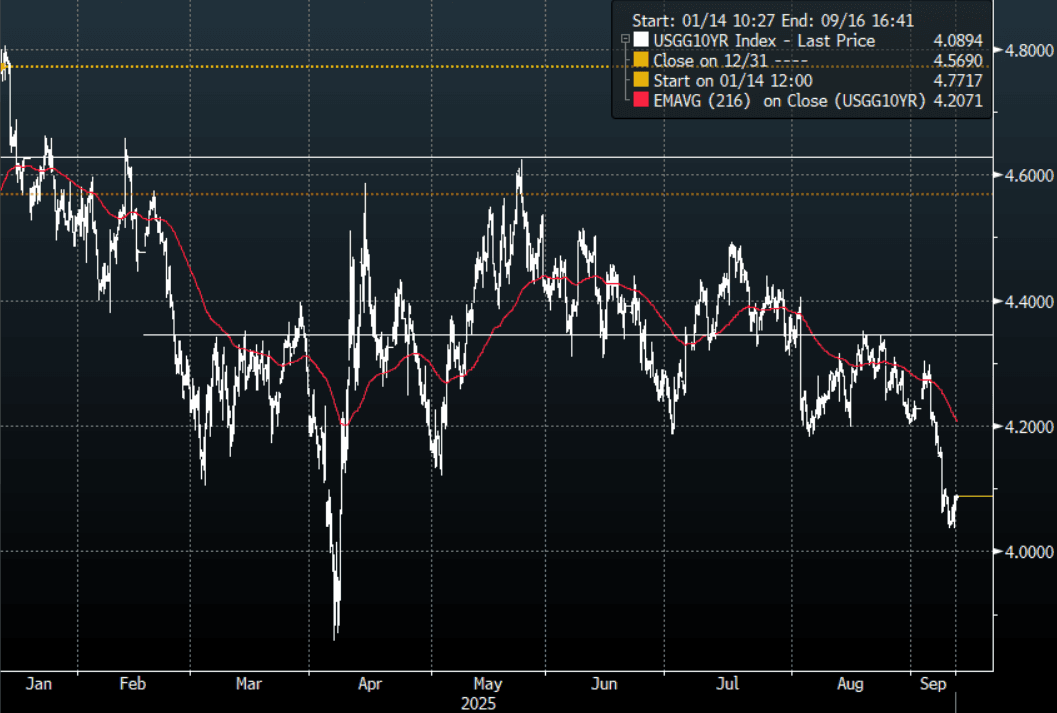
- 10-Year Yields have broken through its support as the market reacts to a labour market that is rapidly cooling. This move should now see buyers return on bounces with the first buy-zone back towards 4.20%. First target the 4.00% zone then the 3.80% area.
- MNI Policy: A federal judge Tuesday night granted a preliminary injunction blocking President Donald Trump from firing Federal Reserve Governor Lisa Cook while her lawsuit challenging her termination is resolved. The FOMC is set to meet again September 16-17.
- MNI US DATA: For PPI, current Bloomberg consensus is for a cooling after July’s hot print, with M/M final demand PPI at 0.3% (0.9% prior) and “core” (ex-food/energy/trade) also at 0.3% (0.6% prior). Core PCE estimates are for 0.31% M/M vs 0.27% prior, with no analysts seeing core PCE printing above core CPI. That could change based on various PPI components that feed into PCE, but as it stands, the M/M core PCE estimate would be the highest since February.
- Given increasing focus on labor risks it’s hard to imagine a set of inflation readings that stops the Fed from cutting 25bp as expected, but it could help shape the updated rate and economic projections to be released at the meeting (including the 2025 “dot” median), as well as Chair Powell’s tone.
- Data/Events: MBA Mortgage Applications, PPI, Wholesale Inventories/Sales
Fig 1: 10-Year US Yield 2H Chart
Source: MNI - Market News/Bloomberg Finance L.P
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
AUD: AUD/USD - Consolidates Above 0.6500, Eyes RBA Tomorrow
The AUD/USD has had a range of 0.6514 - 0.6528 in the Asia- Pac session, it is currently trading around 0.6525, +0.05%. A very quiet start to the week saw AUD/USD consolidate above 0.6500. Risk has traded a little higher in our session, E-minis +15%, NQU5 +0.15%.
- (Bloomberg) - “Reports that AMD and Nvidia will pay 15% of their China revenue to the US government should be a negative for those companies and for tech more broadly. Investors may shrug off the news or even welcome it in the short term as a sign that the companies can go on selling chips to China, but the longer-term outlook is that profit margins may narrow.”
- MNI - The RBA decision is on Tuesday August 12 and is widely expected to cut rates 25bp to 3.60% given the further moderation in underlying inflation in Q2 and signs that the labour market has reached a turning point and is weakening. It had 50bp of easing for H2 assumed in its May projections. There will be an update to the RBA outlook provided with the decision but it is likely to be consistent with the Board's cautious approach to easing.
- Options : Closest significant option expiries for NY cut, based on DTCC data: none. Upcoming Close Strikes : 0.6565(AUD783m Aug 12), 0.6600(AUD1.25b Aug 14) - BBG
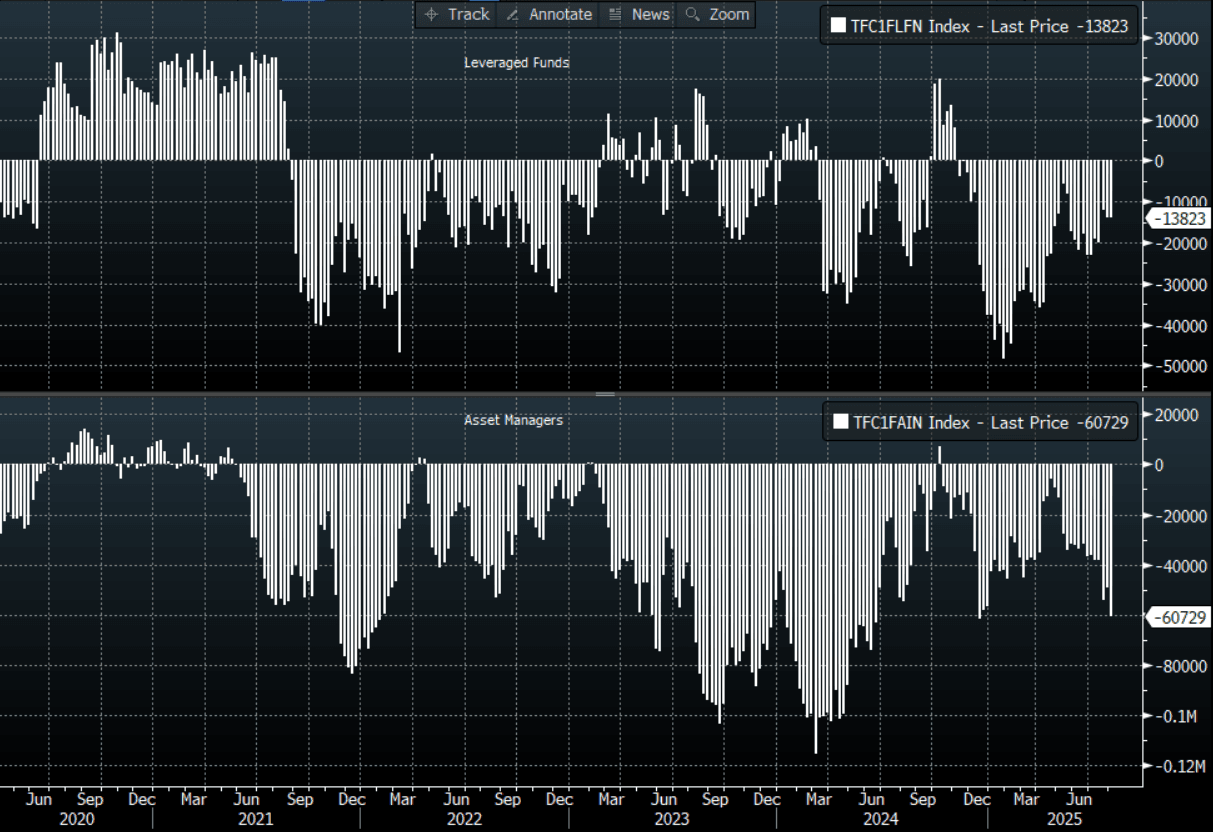
- CFTC Data shows Asset managers added to their shorts -60729(Last -49183), the Leveraged community added very slightly to their own shorts -13997(Last -13823).
- AUD/JPY - Asia-Pac range 96.18 - 96.38, Asia is trading around 96.20. The pair has bounced to test its first resistance around the 96.50 area. There should be sellers around here initially, a sustained break below 94.50/95.00 is needed to signal a deeper move lower or a break above 97.50 would reinstate the momentum higher.
Fig 1: AUD CFTC Data
Source: MNI - Market News/Bloomberg Finance L.P
US TSYS: Futures Trade Slightly Higher
The TYU5 range has been 111-25+ to 111-29+ during the Asia-Pacific session. It last changed hands at 111-29, up 0-02+ from the previous close.
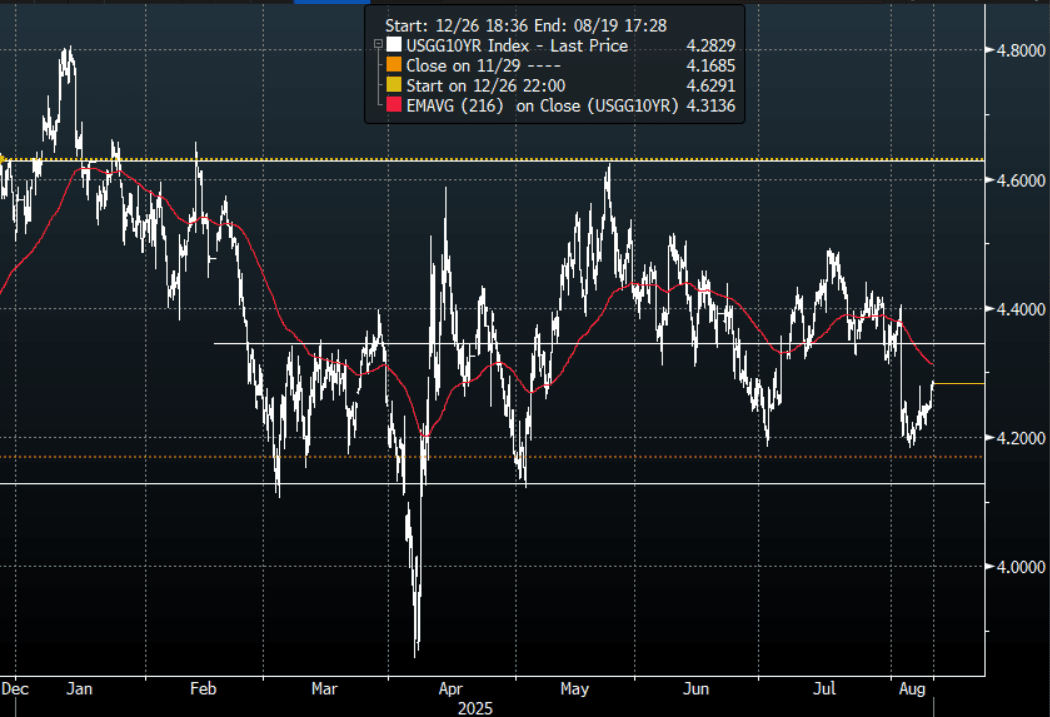
- The 10-year yield had a powerful move lower in reaction to the NFP data, breaking below its 4.30% pivot within the wider range 4.10% - 4.65%. This now turns momentum lower in yields and you could expect buyers of treasuries on bounces back towards 4.30/35% now looking to initially test the 4.10% area.
- Bob Elliott on X: “Used car prices have been a big negative on CPI for the last 3m. A notable difference from the broad trend of underlying used car prices going from a significant disinflationary pressure to a modestly inflationary one over the last year or so.”
MNI DATA - Tuesday’s CPI report headlines the US economic calendar with analysts expecting core CPI inflation to gain momentum in July as the acceleration in core goods inflation continues. We’re starting to get into larger tariff impacts on core goods but the largest could be reserved for Aug-Sep by some estimates. We are currently tracking unrounded core CPI estimates at around 0.32% M/M after the 0.23% in June at what would be the strongest M/M print since January.
Fig 1: 10-Year US Yield 2H Chart
Source: MNI - Market News/Bloomberg Finance L.P
CHINA: Bond Futures Down in Morning Trade
- China's bond futures have begun the week with falls in Monday's morning session.
- After finishing last week up by +0.16, the 10Yr bond future has given all of that back in this morning's session, falling -0.16 to 108.45.
- Having trade last week above the 20-day EMA (of 108.56) the sell off this morning sees the 10Yr track below all major moving averages.
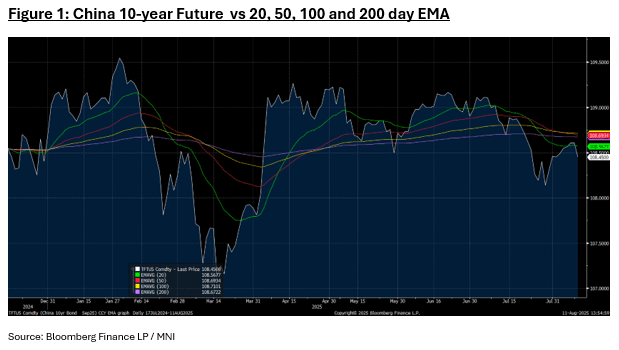
- The 2-year future is lower by -0.01 at 102.35, having traded near to the 20-day EMA of 102.37 before turning lower again.
- The 10YR Government bond has seen yields climb +1.5bp to 1.71%


