US DATA: Another Low Fire, Somewhat Low Hire Jobless Claims Release
Apr-16 12:48
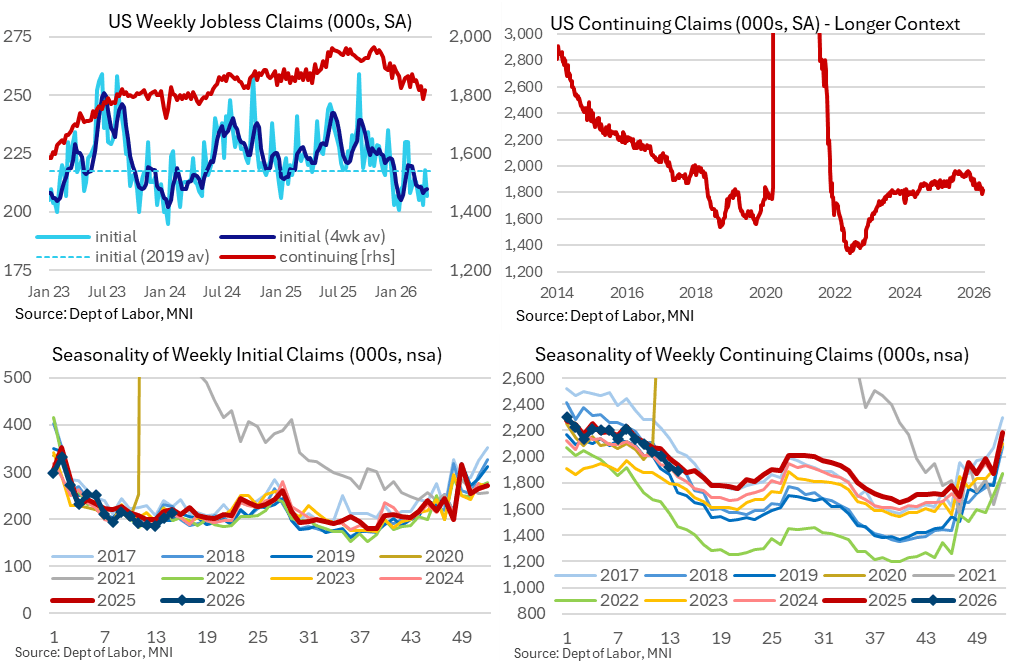
- Initial claims fell to 207k (sa, cons 213k) in the week to Apr 11, just shy of covering a payrolls reference period, after a downward revised 218k (initial 219k).
- Of the 12.1k increase in the non-seasonally adjusted level of claims, 8.3k came from NY. That’s towards the earlier end of typical seasonal distortions but on the small side.
- The four-week average ticked another 1k higher to 210k but is still historically low, for example compared to the 218k averaged in 2019 when the unemloyment rate had a three handle.
- Continuing claims of course remain at a relatively higher (i.e. weaker labor market) level but at least consolidate wwhat's proving a sustained pullback from 2H25.
- Continuing claims increased to 1818k (sa, cons 1810k) in the week to Apr 4 after a downward revised 1787k (initial 1794k).
- The 1787k was its lowest since Apr 2024 whilst the latest 1818k compares with 1844k averaged in 1Q26 and 1931k in 2H25.
- Non-seasonally adjusted levels have pushed below those from 2025 in recent weeks, confirming that the seasonally adjusted profile isn’t due to a more favorable seasonal adjustment process.
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
US DATA: Private Sector Hiring Lost A Little Momentum Heading Towards March
Mar-17 12:26
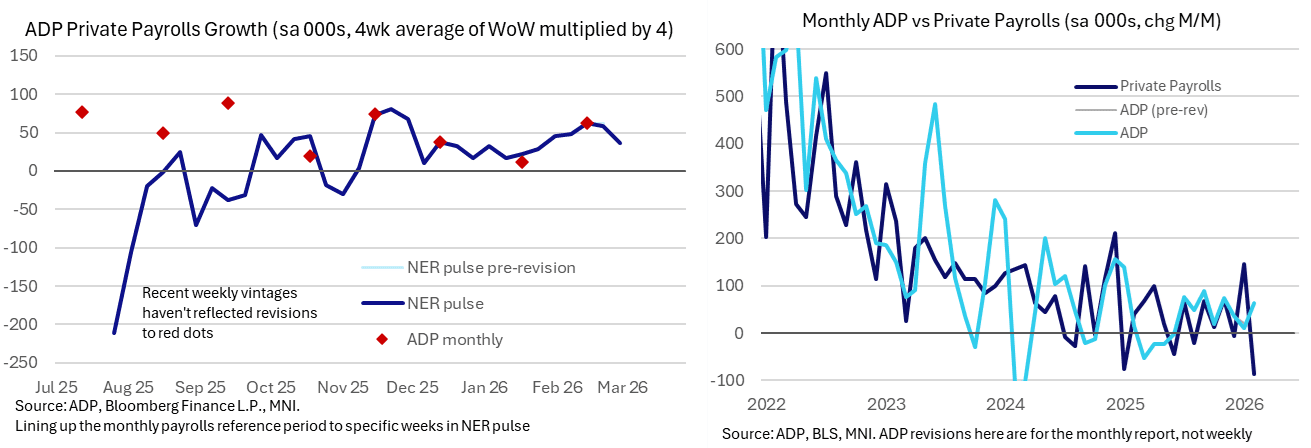
- ADP weekly employment growth cooled a little in today’s update, with an average weekly increase of 9k in the four weeks to Feb 28 after a slightly downward revised 14.75k (initial 15.5k) up to Feb 21 and an unrevised 15.5k up to Feb 14.
- The monthly equivalent of 36k cools from the 63k in the February monthly update released two weeks ago (as always based on a reference week including the 12th day of the month per BLS payrolls) but is above the 11k from January.
- Roughly speaking, this weekly series continues to offer signs of steady but modest private sector job creation compared to some wildly differing indications from the BLS private payrolls data with February’s -86k hit after jumping 146k in January.
OUTLOOK: Price Signal Summary - Gold Remains Above Support
Mar-17 12:14
- On the commodity front, Gold continues to trade below $5419.11, the Mar 2 high. The short-term outlook remains bullish - for now - following the recovery that started Feb 2. The metal has cleared all key retracement points of the sell-off between Jan 29 - Feb 2. This signals scope for an extension towards key resistance and the bull trigger at $5595.5, the Jan 29 high. Initial firm support to watch lies at $4928.6, the 50-day EMA.
- A bull wave in WTI futures remains intact. The recent sharp pullback from the Mar 9 high, has allowed an extreme overbought trend condition to unwind. The key support zone to monitor is $80.37 - $71.03, the area between the 20- and 50-day EMAs. A clear break through this zone would signal a possible trend reversal. On the upside, a continuation higher near-term would open $103.15 next, the 61.8% retracement of the Mar 9 - 10 sell-off.
STIR: Repo Reference Rates Rising
Mar-17 12:06
- Secured Overnight Financing Rate (SOFR): 3.70% (+0.05), volume: $3.178T
- Broad General Collateral Rate (BGCR): 3.67% (+0.04), volume: $1.305T
- Tri-Party General Collateral Rate (TCR): 3.67% (+0.04), volume: $1.277T
- (rate, volume levels reflect prior session)


