US: "*AMAZON SEEKS TO OFFLOAD $8B NVIDIA CHIPS TO INVESTORS: FT" - BBG
"*AMAZON SEEKS TO OFFLOAD $8B NVIDIA CHIPS TO INVESTORS: FT" - BBG...
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
EU: "*MAKHLOUF SAYS ECB MUST BE PREPARED TO LIFT INTEREST RATES: FT
"*MAKHLOUF SAYS ECB MUST BE PREPARED TO LIFT INTEREST RATES: FT
*MAKHLOUF `UNEASY' OVER EUROZONE INFLATION, HE TELLS FT
'*MAKHLOUF TELLS FT ECB DECISION NEXT WEEK WON'T BE A SURPRISE" - BBG"
RBNZ: Timing Of More Hikes Uncertain As MPC Focuses On Economic Impact
RBNZ Governor Breman emphasised that the MPC is not on a “pre-set course” as the level of the neutral rate is highly uncertain as is the economic environment. Her comments suggested that while further tightening is “likely”, the timing is very uncertain as the MPC may want to take time to assess the impact of the 50bp of accommodation reduction as well as new data and information. As a result, a pause in October wasn’t signalled but a hold in coming meetings seems likely. Data remains key and Q3 CPI prints 22 October before the next RBNZ decision on 28 October.
- The RBNZ believes that the long-run neutral rate is little changed but could be higher in the short-term. This uncertainty makes it important for it to take time to monitor the impact of the higher OCR and the MPC is very focussed on observing these effects.
- There was a disagreement over the skew of risks around inflation with Assistant Governor Silk believing they’re to the upside but Chief Economist Conway balanced. Breman emphasised that it is focused on second-round effects causing medium-term inflation persistence.
- Breman noted that household consumption is currently missing from the NZ recovery due to fuel prices, lacklustre labour and housing markets. The recovery remains very uncertain given this and the global environment but there are signs of resilience and so the MPC needs to be flexible.
- While it is a tough labour market, especially for youth and long-term unemployed, job growth is a positive sign, it just hasn’t been able to keep up with the increase in the participation rate. Services recovery is important here as it is a major source of employment.
- The election and currently unclear outcome were not inputs into the September decision but businesses indicated it wasn’t impacting their investment decisions.
- The RBNZ has observed the pass through of the higher OCR to wholesale and mortgage rates but not deposits and it is monitoring the development closely.
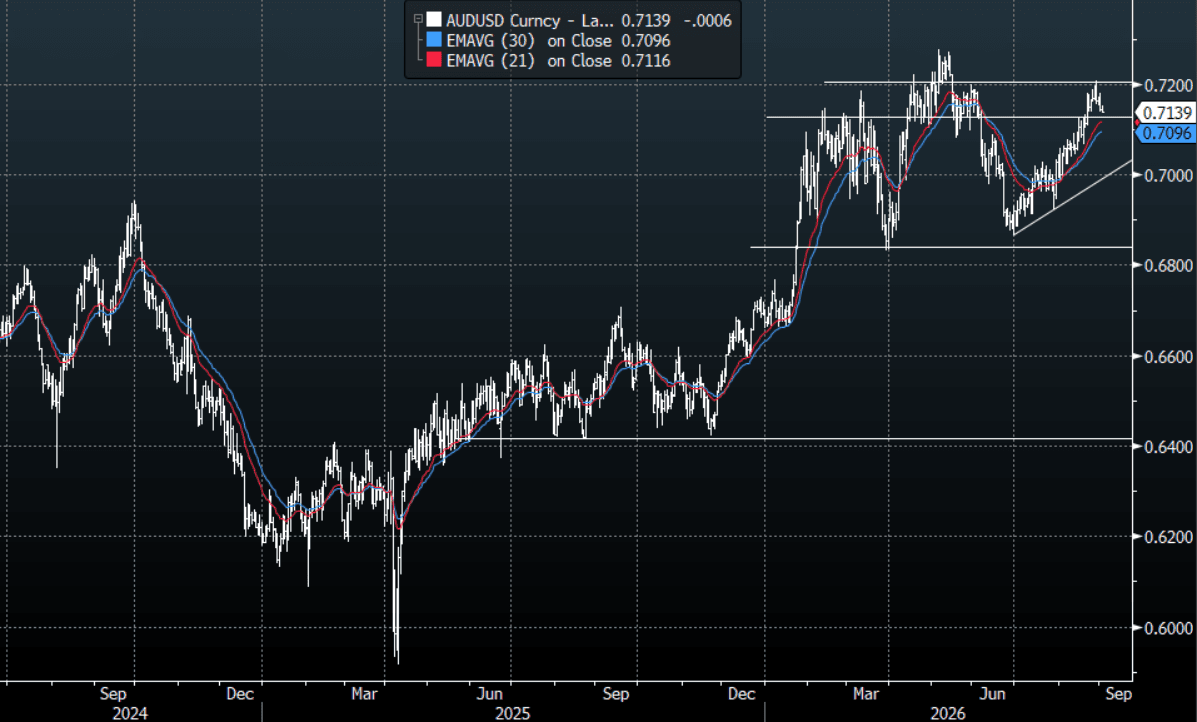
AUD: AUD/USD - Trading Heavy Around 0.7150, Outperforms In The Cross
The AUD/USD has had a range today of 0.7138-0.7154 in the Asia- Pac session, it is currently trading around 0.7140, -0.07%. The pair continues to consolidate around 0.7150 albeit with an offered tone. The Middle-East flare up has seen Oil surge higher and this together with a spike in Global yields is keeping risk on the backfoot. The price action in the US dollar stands out again a little though, with US yields extending higher once more I would have expected a more pronounced reaction from the currency against this current back drop. Is it just lagging or is it something more ? On the day, the first support around 0.7120-0.7150 is currently being challenged, below here the 0.7050-0.7085 area comes back into play. I will be watching to see if the dips remain supported and how the USD fares as the focus now turns to NFP. Expressing AUD outperformance in the crosses has been the better way to go for now as AUD/NZD breaks higher after a combination of diverging local inputs today.
- MNI - AU Weak Productivity & Rising ULC Add To Case For Rate Hike. The Q2 national accounts showed that productivity growth remained elusive in Australia and ran at the same level as the average since Q1 2023 – no improvement for more than three years. The RBA saw this issue as a source of upside risks to its inflation outlook and the Q2 print will add to its concerns and the list of data suggesting another rate hike may be needed to bring underlying inflation back to the band.
- MNI - RBA-Dated OIS Pricing Adds A Full Hike Post-Sept Meetings: After today's GDP release, RBA-dated OIS pricing is 12-30bps firmer than last week's pre-July CPI data levels.
- Options : Closest significant option expiries for NY cut, based on DTCC data: 0.7120(AUD743m), 0.7150(AUD602m). Upcoming Close Strikes : 0.7000(AUD1.2b Sept 4), 0.7100(AUD1b Sept 4), 0.7200(AUD1.17b Sept 4) - BBG
- The AUD/USD Average True Range for the last 10 Trading days: 33 Points
Fig 1: AUD/USD spot Daily Chart
Source: MNI - Market News/Bloomberg Finance L.P


